
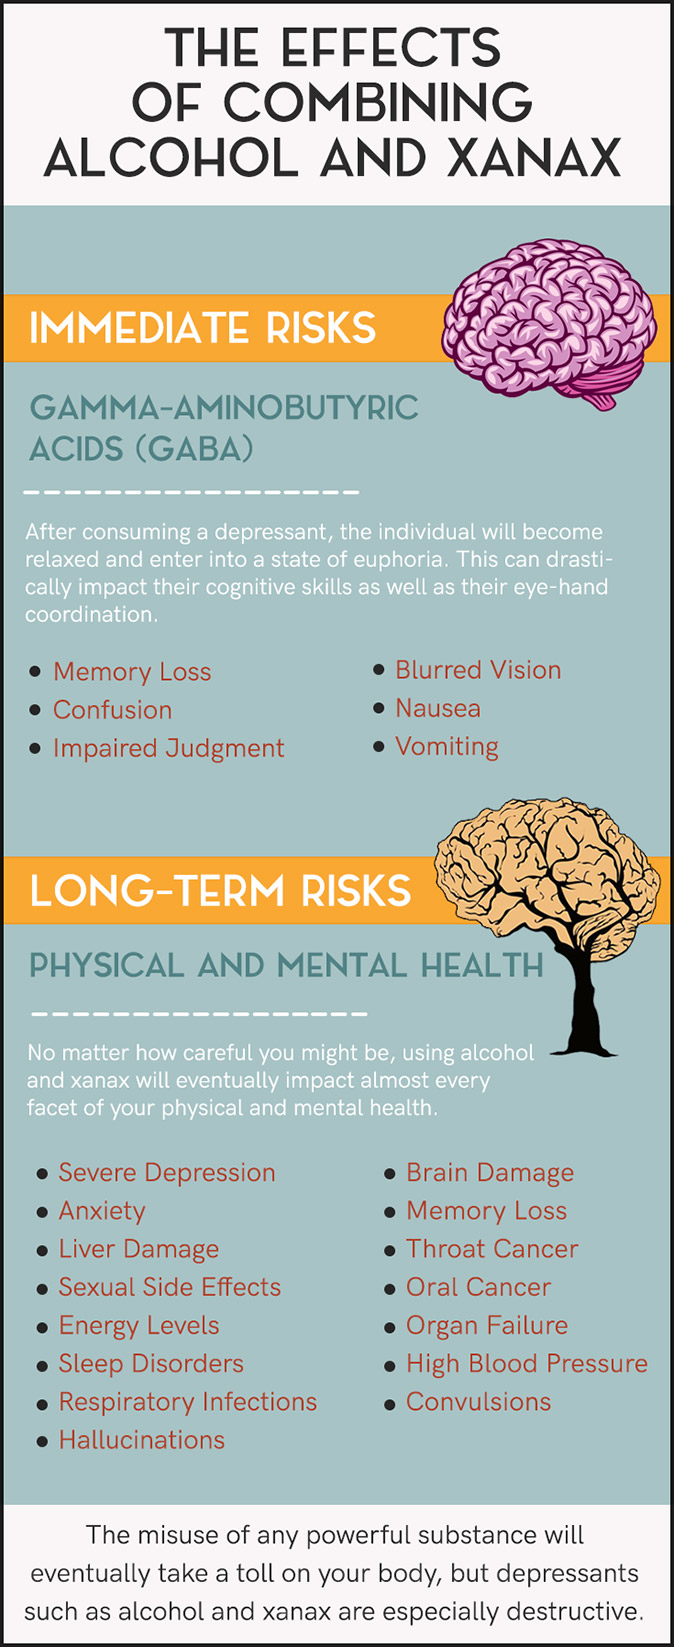
While much of the public discourse surrounding the concurrent use of benzodiazepines and alcohol focuses on the immediate physiological dangers, there is a profound and often overlooked dimension to this crisis: the catastrophic financial and professional fallout. In the realms of personal finance and wealth management, the “mixing” of Xanax and alcohol represents one of the single greatest threats to a liquid portfolio, career trajectory, and long-term insurability. To understand what happens when these two substances intersect is to understand a sequence of events that can lead to the total destabilization of a professional life and the depletion of decades of accumulated capital.
The Immediate Financial Impact: Emergency Intervention and Medical Debt
The intersection of Xanax (alprazolam) and alcohol is not merely a health crisis; it is a high-cost financial event. From an accounting perspective, the immediate aftermath of a polysubstance incident involves a series of unbudgeted, high-velocity expenses that can disrupt even a robust emergency fund.
The Cost of Acute Medical Care
When an individual suffers from the synergistic effects of these substances—which include severe respiratory depression and loss of consciousness—the entry point into the financial system is often the Emergency Room (ER). In the United States, the average cost of an ER visit for a drug-related emergency can range from $2,500 to $10,000, depending on the level of intervention required. If intubation or intensive care unit (ICU) monitoring is necessary, these costs escalate exponentially. For those with high-deductible health plans (HDHPs), this single night can result in the total exhaustion of an annual out-of-pocket maximum within hours.
Deductibles, Co-Insurance, and Out-of-Network Penalties
The financial burden is rarely limited to the hospital bill itself. The complexity of medical billing means that “mixing” often leads to a cascade of surprise invoices. Anesthesiologists, toxicologists, and laboratory services may be billed as out-of-network providers, even if the hospital itself is in-network. For the personal financier, this represents a massive “leakage” of capital that provides zero return on investment, fundamentally altering the year’s savings rate and potentially forcing the liquidation of assets to cover the debt.
Career Destabilization and the Loss of Lifetime Earning Power
Beyond the immediate medical invoices, the combination of Xanax and alcohol acts as a corrosive agent on a professional’s “human capital”—the present value of their future earnings. In corporate finance and personal branding, reputation is a primary asset. When substance misuse becomes visible within a professional setting, the depreciation of that asset is swift and often permanent.
Impact on High-Stakes Professional Licenses
For those in the financial services, legal, or medical sectors, the consequences of a substance-related incident are quantified by the loss of licensure. Regulatory bodies like FINRA or state bar associations have strict reporting requirements for alcohol and drug-related incidents. A single lapse in judgment involving Xanax and alcohol can lead to the suspension or revocation of professional designations. From a “Money” perspective, the loss of a Series 7 license or a law license represents the destruction of a multi-million dollar asset (the ability to practice in a high-income field).
Decreased Productivity and “Presenteeism”
Even if an individual avoids a catastrophic medical event, the chronic “mixing” of these substances leads to a phenomenon known as “presenteeism”—where an employee is physically present but cognitively impaired. In the fast-paced world of trading, fintech, or corporate strategy, the loss of cognitive edge is financially measurable. Decisions made under the residual haze of alprazolam and ethanol can lead to poor investment choices, botched negotiations, and missed opportunities, ultimately resulting in passed-over promotions and stagnant salary growth.
Actuarial Consequences: The Long-Term Impact on Insurance and Estate Planning
In the world of wealth management, risk mitigation is as important as wealth accumulation. Mixing Xanax and alcohol creates an actuarial profile that insurance companies view as high-risk, which has direct implications for the cost of protecting one’s estate.
Life and Disability Insurance Premiums
When applying for life insurance or long-term disability (LTD) coverage, underwriters conduct a deep dive into medical records. A history of polysubstance use—specifically the combination of a controlled substance and alcohol—is a massive red flag. For the individual, this results in “rated” policies, where premiums can be 200% to 500% higher than standard rates. In some cases, coverage may be denied entirely. For a high-net-worth individual looking to use life insurance as a tool for estate liquidity or wealth transfer, this denial can derail a comprehensive financial plan, leaving heirs with significant tax liabilities that could have otherwise been mitigated.
Health Insurance Underwriting and Policy Gaps
While the Affordable Care Act (ACA) prevents denials based on pre-existing conditions, it does not prevent certain gaps in coverage related to substance use. Many private disability policies contain “self-inflicted injury” or “substance abuse” exclusions. If a professional becomes unable to work due to the neurological or cognitive damage caused by mixing Xanax and alcohol, they may find their claims denied. This leaves the individual without a primary income stream at the very moment their medical expenses are peaking, a scenario that often leads to personal bankruptcy.
The Macroeconomic Perspective: Business Productivity Loss
The issue of mixing substances extends beyond the individual to the corporate balance sheet. For business owners and executives, the “Xanax and alcohol” problem is a line-item expense that affects the bottom line.
Corporate Health Plan Inflation
Employers who sponsor health insurance plans bear the brunt of substance-related healthcare costs. High-cost claims resulting from addiction-related incidents drive up the overall premiums for the entire group. In an era where companies are looking to lean out operations, the rising cost of employee benefits—driven in part by the benzodiazepine and opioid crisis—reduces the capital available for R&D, expansion, or shareholder dividends.
Turnover and Recruitment Costs
When a key executive or high-performing employee is lost due to the consequences of substance mixing, the business incurs significant “replacement costs.” Industry data suggests that replacing a senior-level executive can cost between 150% and 213% of their annual salary. This includes recruitment fees, onboarding time, and the “knowledge drain” that occurs when a pivotal player exits the organization under duress.
Strategic Financial Recovery: Navigating the High Cost of Rehabilitation
If an individual chooses to address the issue, they are met with another significant financial hurdle: the cost of recovery. In the niche of financial planning for healthcare, the cost of rehabilitation is a major consideration.
The Price of High-End Recovery Facilities
For the high-earning professional, “standard” rehab is often eschewed in favor of executive recovery centers that allow for some level of continued business activity. These facilities can cost anywhere from $30,000 to $100,000 per month. Without a dedicated “health sinking fund” or specialized insurance coverage, this expense often requires withdrawing funds from retirement accounts.
Tax Implications and Early Withdrawal Penalties
Liquidating a 401(k) or IRA to pay for rehabilitation is a double-edged sword. Not only is the capital removed from a tax-advantaged growth environment, but it is also subject to immediate income tax and, if the individual is under 59.5, a 10% early withdrawal penalty. While certain “hardship withdrawals” or medical expense deductions (exceeding 7.5% of Adjusted Gross Income) may apply, the long-term cost of lost compound interest is a price that many professionals pay for decades.
Wealth Preservation Through Sobriety
Ultimately, the most effective financial strategy for anyone prescribed Xanax is the strict avoidance of alcohol. From a purely economic standpoint, sobriety is a high-yield investment. It preserves human capital, protects reputation, minimizes insurance premiums, and ensures that the wealth accumulated over a lifetime is not diverted to the “black hole” of medical debt and legal fees.
In the complex landscape of personal finance, we often talk about market volatility, tax law changes, and inflationary pressures. However, few things are as volatile or as damaging to a financial portfolio as the decision to mix Xanax with alcohol. It is a decision that triggers a negative compounding effect, where health, career, and capital all decline simultaneously. For those focused on building and maintaining wealth, understanding the financial reality of this interaction is just as crucial as understanding any market indicator. The cost of “mixing” is simply too high for any rational investor to bear.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.