
In the world of personal finance and wealth management, we often spend an inordinate amount of time discussing the “source” of our income. We focus on career advancement, the launch of new side hustles, and the optimization of active revenue streams. However, to achieve true financial mastery, one must look downstream. If your financial life is a river, the “mouth” is the ultimate destination where your capital is deployed, utilized, or preserved.
The mouth of the river represents the point of impact—the transition from raw currency into realized value, whether that be lifestyle fulfillment, debt elimination, or long-term legacy building. Understanding what the mouth of your financial river looks like is the difference between a system that nourishes a fertile delta and one that simply disappears into a desert of uncontrolled expenses.
Defining the Financial Mouth: Where Income Becomes Impact
In geography, the mouth of a river is where it meets another body of water, such as an ocean or a lake. In finance, the mouth is the point where your liquidity transforms into an asset, a memory, or a protection. Many individuals suffer from a “leaky” riverbed, where capital evaporates through hidden fees and lifestyle creep before it ever reaches a meaningful destination.
The Purpose of the Outflow
Every dollar you earn should have a mission. When we ask, “What is the mouth of the river?” we are essentially asking, “What is the ultimate goal of this capital?” For some, the mouth is a robust retirement portfolio that provides permanent autonomy. For others, it is the funding of a philanthropic foundation or the purchase of real estate that will house future generations. By identifying the destination, you can better engineer the flow. If you do not define the mouth of your river, your money will naturally flow toward the path of least resistance: impulse spending and low-value consumption.
Liquidity and Velocity
The speed at which your money moves toward its destination is known as financial velocity. A healthy financial river doesn’t stagnate; it flows with purpose. High-velocity systems ensure that cash is not sitting idle in low-interest accounts but is instead moving toward the mouth—be it a brokerage account, a high-yield savings vehicle for a specific goal, or the principal of a high-interest debt. Understanding the mouth allows you to measure whether your money is moving fast enough to meet your long-term objectives.
Mapping the Tributaries: Identifying Your Diversified Revenue Streams
Before a river reaches its mouth, it is fed by various tributaries. In a sophisticated financial model, these are your diversified income streams. Relying on a single source of income is akin to a river that dries up during a single season of drought. To ensure a consistent flow to your financial destination, you must develop a network of tributaries that can withstand various economic climates.
Active vs. Passive Inflows
The primary tributary for most professionals is active income—the salary or fee-for-service model. While this provides the initial volume, it is often the most taxed and least scalable. To truly widen the mouth of your financial river, you must integrate passive tributaries. This includes dividend-paying stocks, rental income from real estate, and digital products or intellectual property. These streams continue to flow even when you are not actively “steering” the river, ensuring that the destination remains well-funded regardless of your personal labor capacity.
Scaling Side Hustles into Main Currents
In the modern economy, side hustles act as experimental tributaries. They allow individuals to test new markets and skills with minimal risk. However, the goal of a side hustle should always be to either increase the total volume of the river or to provide a backup channel should the main current fail. Tools like automated bookkeeping software and AI-driven marketing platforms have made it easier than ever to scale these small streams into significant forces. When a side hustle begins to rival your primary income, your financial “delta” expands, allowing for more complex investment strategies at the mouth.
The Delta of Investment: Allocating Capital for Maximum Growth
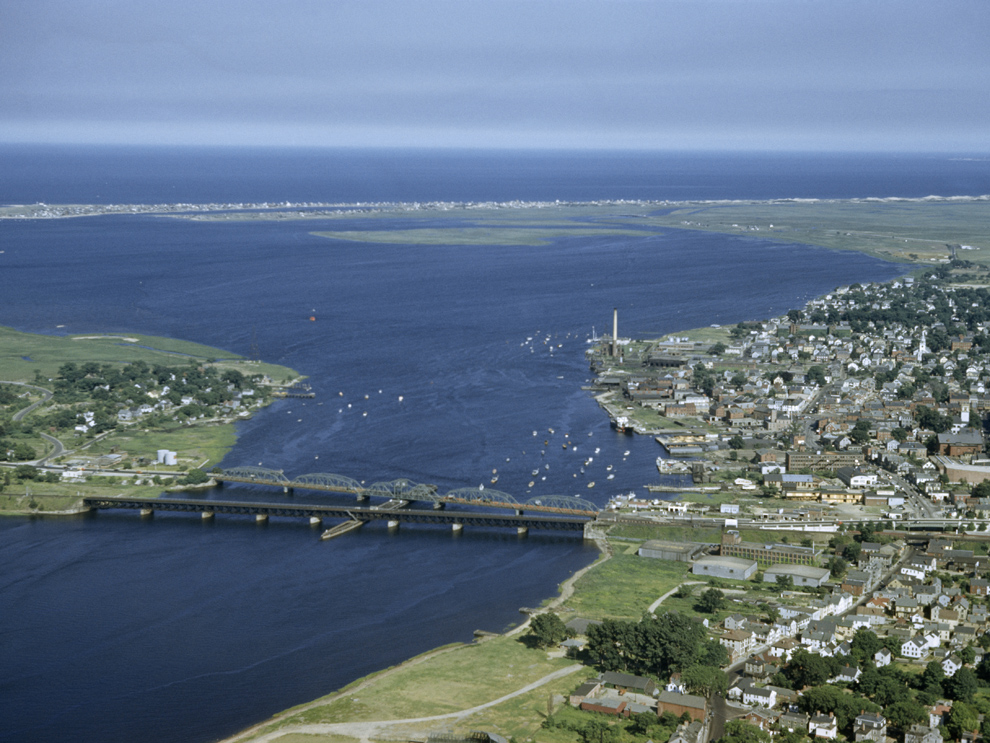
As a river nears its mouth, it often slows down and spreads out into a delta—a rich, fertile area where deposits are made. In finance, this is the phase of strategic capital allocation. This is where you decide how much of your flow goes into high-growth equities, how much into stable bonds, and how much into speculative but potentially high-reward ventures like venture capital or cryptocurrency.
Strategic Asset Allocation
The way you distribute your capital in the “delta” determines the long-term health of your financial ecosystem. Professional investors use modern portfolio theory to ensure that their assets are not all concentrated in one area. By spreading the flow across different sectors and geographies, you protect the mouth of your river from localized economic “droughts.”
- Equities: The engine of growth, providing long-term appreciation.
- Fixed Income: The stabilizer, ensuring that the flow remains steady during market volatility.
- Real Assets: Tangible wealth, such as real estate or gold, which acts as a hedge against the erosion of the currency’s value.
Avoiding the “Evaporation” of Unmanaged Funds
One of the greatest threats to the financial delta is “slippage”—the small, often unnoticed costs that drain wealth. This includes high management fees in mutual funds, excessive trading commissions, and the “tax drag” created by inefficient portfolio rebalancing. Using financial tools like low-cost index funds and tax-loss harvesting software can help ensure that more of your money reaches its intended destination rather than being siphoned off by intermediaries.
Managing the Surge: Protecting Your Financial System from Volatility
Just as a physical river can flood, a financial system can experience “surges” of volatility or unexpected expenses. Without proper infrastructure, these surges can wash away years of progress. Protecting the mouth of your river requires the construction of financial “levees”—protective measures that keep your capital on track even during storms.
Emergency Funds and Liquidity Buffers
The first line of defense is the emergency fund. This is a reservoir of liquid cash (typically three to six months of expenses) that sits outside the main flow. It ensures that if one of your tributaries dries up—such as a job loss or a business downturn—you do not have to “drain” the investments at the mouth of your river to survive. This buffer allows your long-term assets to remain undisturbed, benefiting from the power of compounding interest.
Risk Mitigation through Insurance
Insurance is often overlooked as a financial tool, but it is a critical component of wealth preservation. Whether it is disability insurance to protect your active income stream or umbrella liability insurance to protect your accumulated assets, these products act as a bulkhead. They ensure that a single catastrophic event—be it legal, medical, or environmental—does not divert the entire flow of your financial life toward a third party.
The Ocean of Legacy: Planning for Long-term Wealth Preservation
Ultimately, every river reaches the ocean. In financial terms, this is your legacy—the state of your wealth after you no longer need it to fund your daily life. This is where personal finance evolves into estate planning and generational wealth management.
Tax Efficiency and Estate Governance
If you do not plan for the “ocean,” the government often becomes the primary beneficiary of your life’s work. Strategic use of trusts, tax-advantaged accounts (like 404(k)s or IRAs), and charitable giving strategies can ensure that the mouth of your river flows into the hands of your heirs or the causes you care about. Proper estate governance involves more than just a will; it requires a comprehensive strategy that considers gift taxes, inheritance laws, and the transition of private business interests.

The Psychological Shift from Accumulation to Decumulation
Perhaps the most difficult part of understanding the mouth of the river is the psychological transition from “gathering” to “distributing.” For decades, the focus is on increasing the flow. However, as you reach the mouth, the focus must shift toward sustainable withdrawal rates and the enjoyment of the “fertile land” you have created. Financial tools like retirement calculators and Monte Carlo simulations can provide the confidence needed to transition from the active work of a “tributary” to the peaceful observation of the “ocean.”
In conclusion, the question “What is the mouth of the river?” is a call to look at the big picture of your financial life. It is not enough to simply earn; you must have a destination. By defining your goals, diversifying your income, protecting your assets, and planning for your legacy, you ensure that your financial river doesn’t just run dry, but instead creates a lasting, meaningful impact.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.