
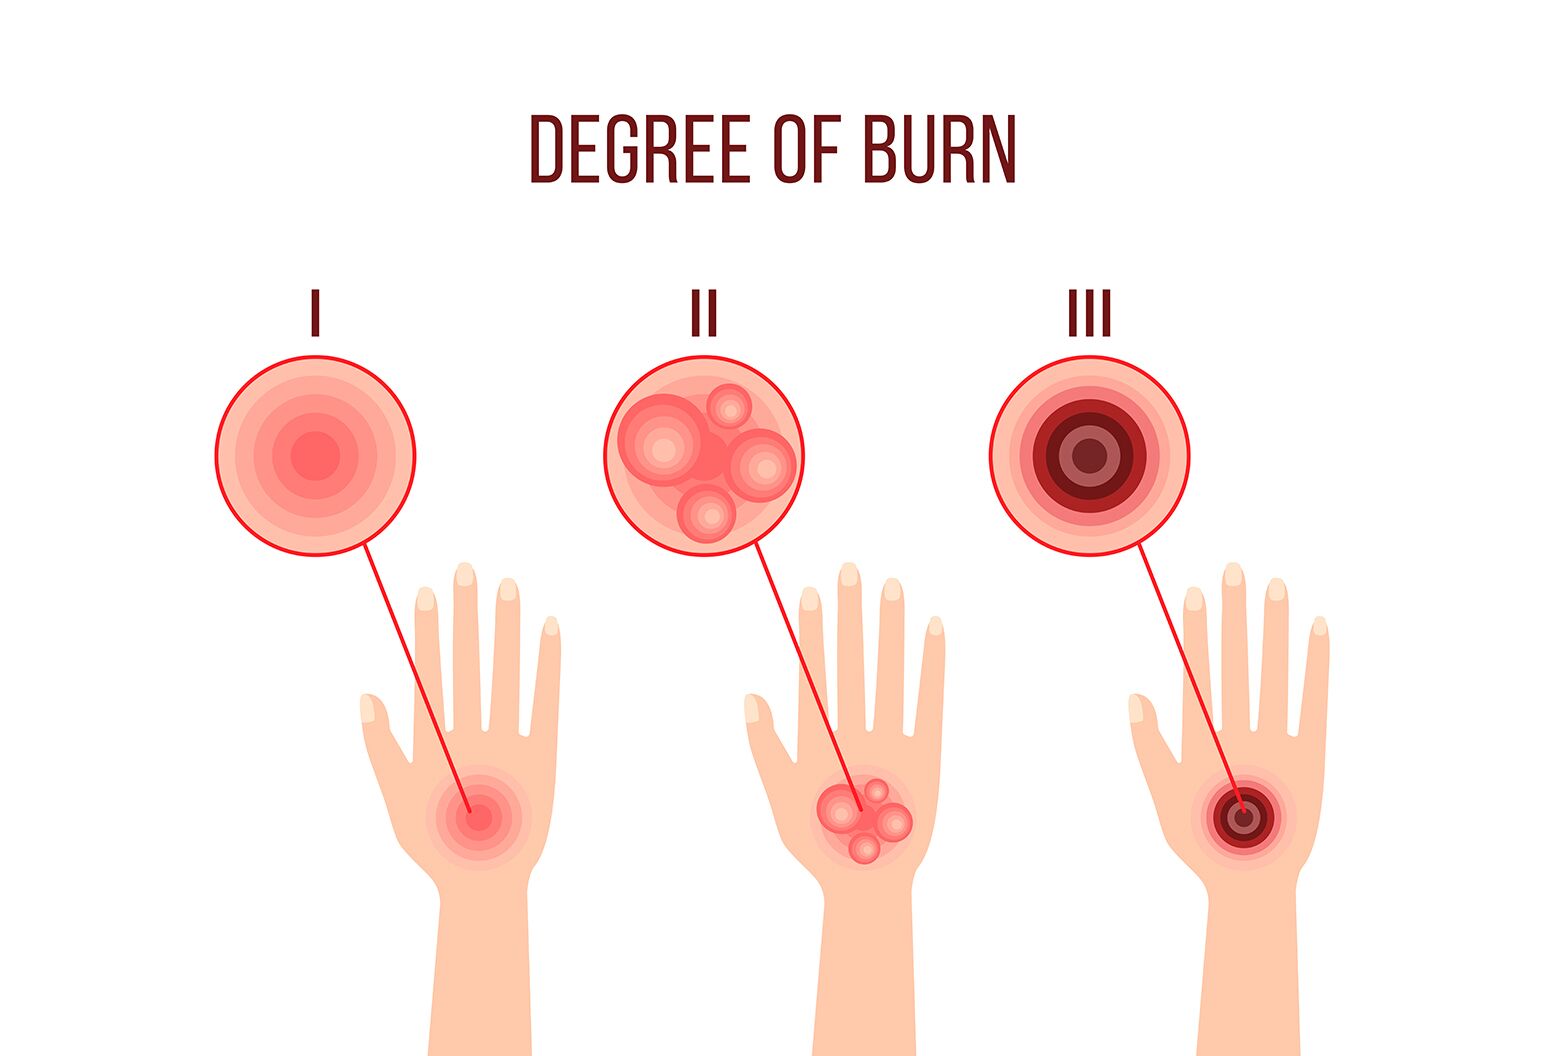
In the high-stakes world of venture capital, corporate expansion, and personal wealth management, the term “burn” is frequently utilized to describe the rate at which an entity spends its capital before generating a positive cash flow. However, not all financial burns are created equal. Just as in medical terminology, a “First Degree Burn” in finance represents a surface-level, manageable loss of capital that serves as a critical warning sign rather than a catastrophic failure.
A first-degree financial burn occurs when an organization or an individual experiences a short-term deficit where expenditures exceed income, but the core “dermis” of the financial structure remains intact. Understanding this phenomenon is essential for entrepreneurs, investors, and individuals looking to maintain long-term solvency while pursuing growth.
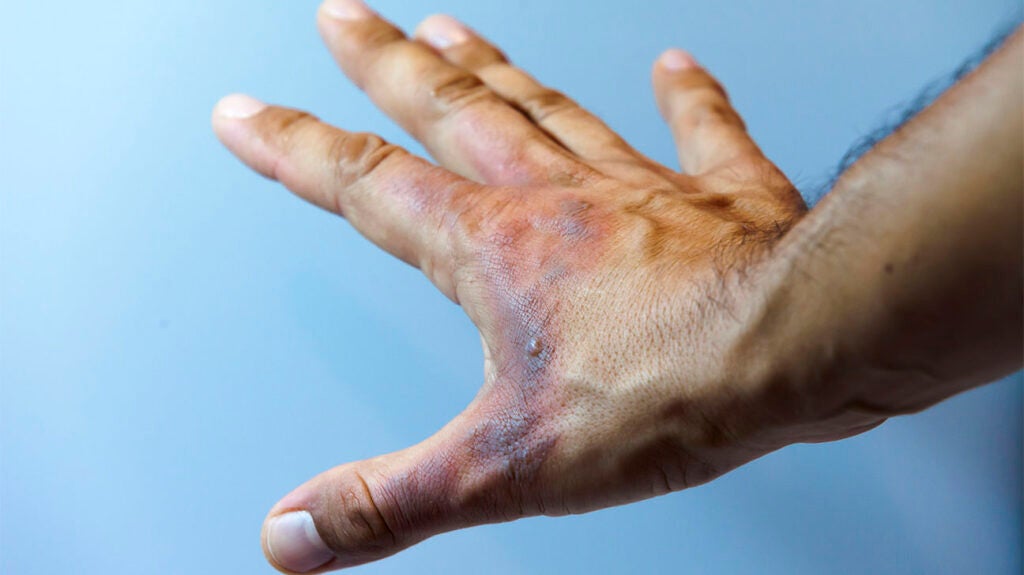
The Financial Anatomy of a First Degree Burn
To understand the first degree burn, one must first understand the fundamental concept of the “burn rate.” In a business context, the burn rate is the pace at which a company uses up its venture capital to finance overhead before it starts generating its own positive cash flow. When we categorize this as a “first degree” event, we are looking at the initial stages of capital depletion—often planned, sometimes unexpected, but always requiring immediate attention to prevent deeper “tissue” damage to the balance sheet.
Defining the Surface-Level Deficit
A first-degree burn is characterized by its reach. It typically affects the liquid assets—the cash on hand or the immediate operating budget—without yet threatening the long-term viability of the enterprise or the individual’s core assets (such as real estate, retirement accounts, or intellectual property). In personal finance, this might look like a month where credit card spending exceeds the monthly salary, necessitating a small withdrawal from a standard savings account. In a corporate setting, it might be a quarterly loss driven by a specific marketing push or a seasonal dip in sales.
The Warning Signal: Why the First Degree Matters
The primary characteristic of a first-degree burn is its role as a diagnostic tool. Because it is non-lethal, it allows for a “course correction.” It signals that the current trajectory is unsustainable if left unchecked. If a startup is burning $50,000 more a month than it anticipated, it hasn’t failed yet, but it has reached a “first degree” state. This is the optimal time to re-evaluate the business model, tighten operational efficiencies, and look for “leaks” in the budget.
Navigating the Burn in Startup Ecosystems
For startups, the burn rate is a badge of honor and a source of constant anxiety. High-growth tech companies often operate in a state of intentional financial burn for years to capture market share. However, the transition from a controlled first-degree burn to a deep, third-degree fiscal crisis can happen rapidly if management loses sight of the metrics.
Burn Rate as a Growth Metric
Investors often look at the burn rate to determine a company’s “runway”—the amount of time the company has before it runs out of money. A first-degree burn is often seen as an investment in the future. If a SaaS company is spending heavily on customer acquisition (CAC), they are “burning” cash today to secure subscription revenue for the next five years. The key is ensuring that the Lifetime Value (LTV) of the customer significantly outweighs the cost of the burn.
Managing the Runway
The “runway” is the ultimate measurement of how long a first-degree burn can be sustained. If a company has $1 million in the bank and a monthly first-degree burn of $100,000, its runway is ten months. Managing this runway involves a delicate balance:
- Aggressive Scaling: Increasing the burn to capture the market faster.
- Conservative Preservation: Reducing the burn to extend the runway while waiting for a more favorable economic climate.
- Pivoting: Using the remaining capital to shift the business model if the current one isn’t yielding the expected return on the burn.
The Dangers of “Burn Fatigue”
There is a psychological component to the first-degree burn in business. When a company is constantly operating in the red, even if it is intentional, “burn fatigue” can set in. This leads to a desensitization toward losses. Founders may begin to view a $10,000-a-month loss as “normal,” failing to realize when that loss begins to deepen into a second-degree burn, where debt begins to accumulate and equity must be sold at a discount just to survive.
Personal Finance: Identifying Your Household Burn Rate
While the term “burn rate” is often relegated to the boardroom, it is equally applicable to personal finance. Every household has a burn rate—the total of all monthly expenses compared to total monthly income. A “First Degree Burn” in a personal context is the moment your lifestyle exceeds your earnings.
The “Lifestyle Creep” Phenomenon
Lifestyle creep is the most common cause of a first-degree financial burn. As individuals earn more, they tend to spend more. However, when an unexpected expense arises—or when income stagnates—the high spending remains. The first-degree burn is that uncomfortable feeling when you realize you are “living paycheck to paycheck” despite a high salary. It is the surface-level erosion of your financial security.
Distinguishing Between Good and Bad Debt
Not all first-degree burns are negative. Much like a business investing in a marketing campaign, an individual might experience a temporary burn by taking on a student loan or a mortgage. This is a strategic burn: you are spending capital (or future capital) to acquire an asset or a skill that will eventually reverse the burn and lead to wealth accumulation. The “burn” only becomes a medical-grade emergency when the debt is used to fund depreciating assets or daily consumption.
The Importance of the Emergency Fund
The “aloe vera” for a first-degree financial burn is the emergency fund. This fund is designed to absorb the heat of unexpected expenses—a car repair, a medical bill, or a brief period of unemployment—without forcing the individual to tap into high-interest credit or long-term investments. Without an emergency fund, a first-degree burn quickly escalates, leading to the liquidation of assets or the accumulation of toxic debt.
Strategic Cooling: How to Recover from Capital Loss
Once a first-degree burn has been identified, whether in a multi-million dollar corporation or a personal budget, the goal is “cooling” the financial structure. This involves a two-pronged approach: reducing outflows and optimizing inflows.
Audit and Optimization
The first step in treating a first-degree burn is a comprehensive audit. In business, this means looking at “SaaS sprawl” (unused software subscriptions), bloated payrolls, or inefficient marketing channels. In personal finance, it means tracking every dollar spent for 30 days to identify where the “heat” is coming from.
- The 80/20 Rule: Often, 80% of the financial burn comes from 20% of the activities. Identifying and trimming these “hot spots” can provide immediate relief.
- Negotiation: Refinancing high-interest debt or renegotiating vendor contracts can lower the burn rate without sacrificing quality of life or business operations.
Revenue Acceleration
The most effective way to stop a burn is to increase the fire of revenue. For a business, this might mean a short-term promotion to boost cash flow or a shift in focus toward high-margin products. For an individual, it might involve a “side hustle,” pursuing a promotion, or selling unused assets to replenish the cash reserves.
Leveraging Financial Tools
In the modern economy, technology provides the cooling mechanism for financial burns. AI-driven budgeting apps, real-time financial dashboards, and automated savings tools allow for the “early detection” of a first-degree burn. By setting alerts for when spending exceeds a certain threshold, users can address the burn before it penetrates the deeper layers of their financial health.
Moving Beyond the Burn: Building Wealth Resilience
The goal of any entity should be to move from a state of “burn” to a state of “compounding.” When you are no longer experiencing a first-degree burn, every extra dollar earned is not just “healing” a wound, but building a fortress.
From Burn to Surplus
Once the burn is extinguished, the surplus capital must be deployed strategically. In business, this is reinvested into R&D or returned to shareholders. In personal finance, this is directed toward the “Wealth Snowball”—investing in assets that generate their own income, effectively creating a “reverse burn” where your money earns money faster than you can spend it.
Resilience Against Future Heat
Financial resilience is the ability to withstand a first-degree burn without it ever becoming a second or third-degree crisis. This is achieved through:
- Diversification: Multiple streams of income (business) or diverse investment portfolios (personal).
- Liquidity: Maintaining enough cash-on-hand to cover 6-12 months of “burn” if income were to stop entirely.
- Low Fixed Costs: Keeping the “essential” burn rate low allows for more flexibility during economic downturns.
Understanding the first-degree burn is about understanding the boundary between healthy growth and unsustainable loss. It is the metric that tells you when to push forward and when to pull back. By recognizing the signs of surface-level financial erosion early, you can implement the necessary strategies to protect your capital, extend your runway, and eventually reach a state of permanent financial health.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.