
Baptism is a significant milestone that marks the beginning of a child’s journey within a community. While traditional gifts such as silver rattles, heirloom clothing, or religious iconography have their place in history, a modern shift is occurring toward gifts that provide long-term utility and security. In an era of economic volatility and rising costs of living, the most profound gift a godparent or family member can provide is a head start on financial independence.
Choosing a financial gift for a baptism is an act of foresight. It moves the focus from immediate sentimentality to the strategic accumulation of wealth. By leveraging the power of time and compound interest, a modest contribution today can transform into a substantial asset by the time the child reaches adulthood. This guide explores the most effective financial instruments and wealth-building strategies to consider when deciding what to give as a gift for a baptism.
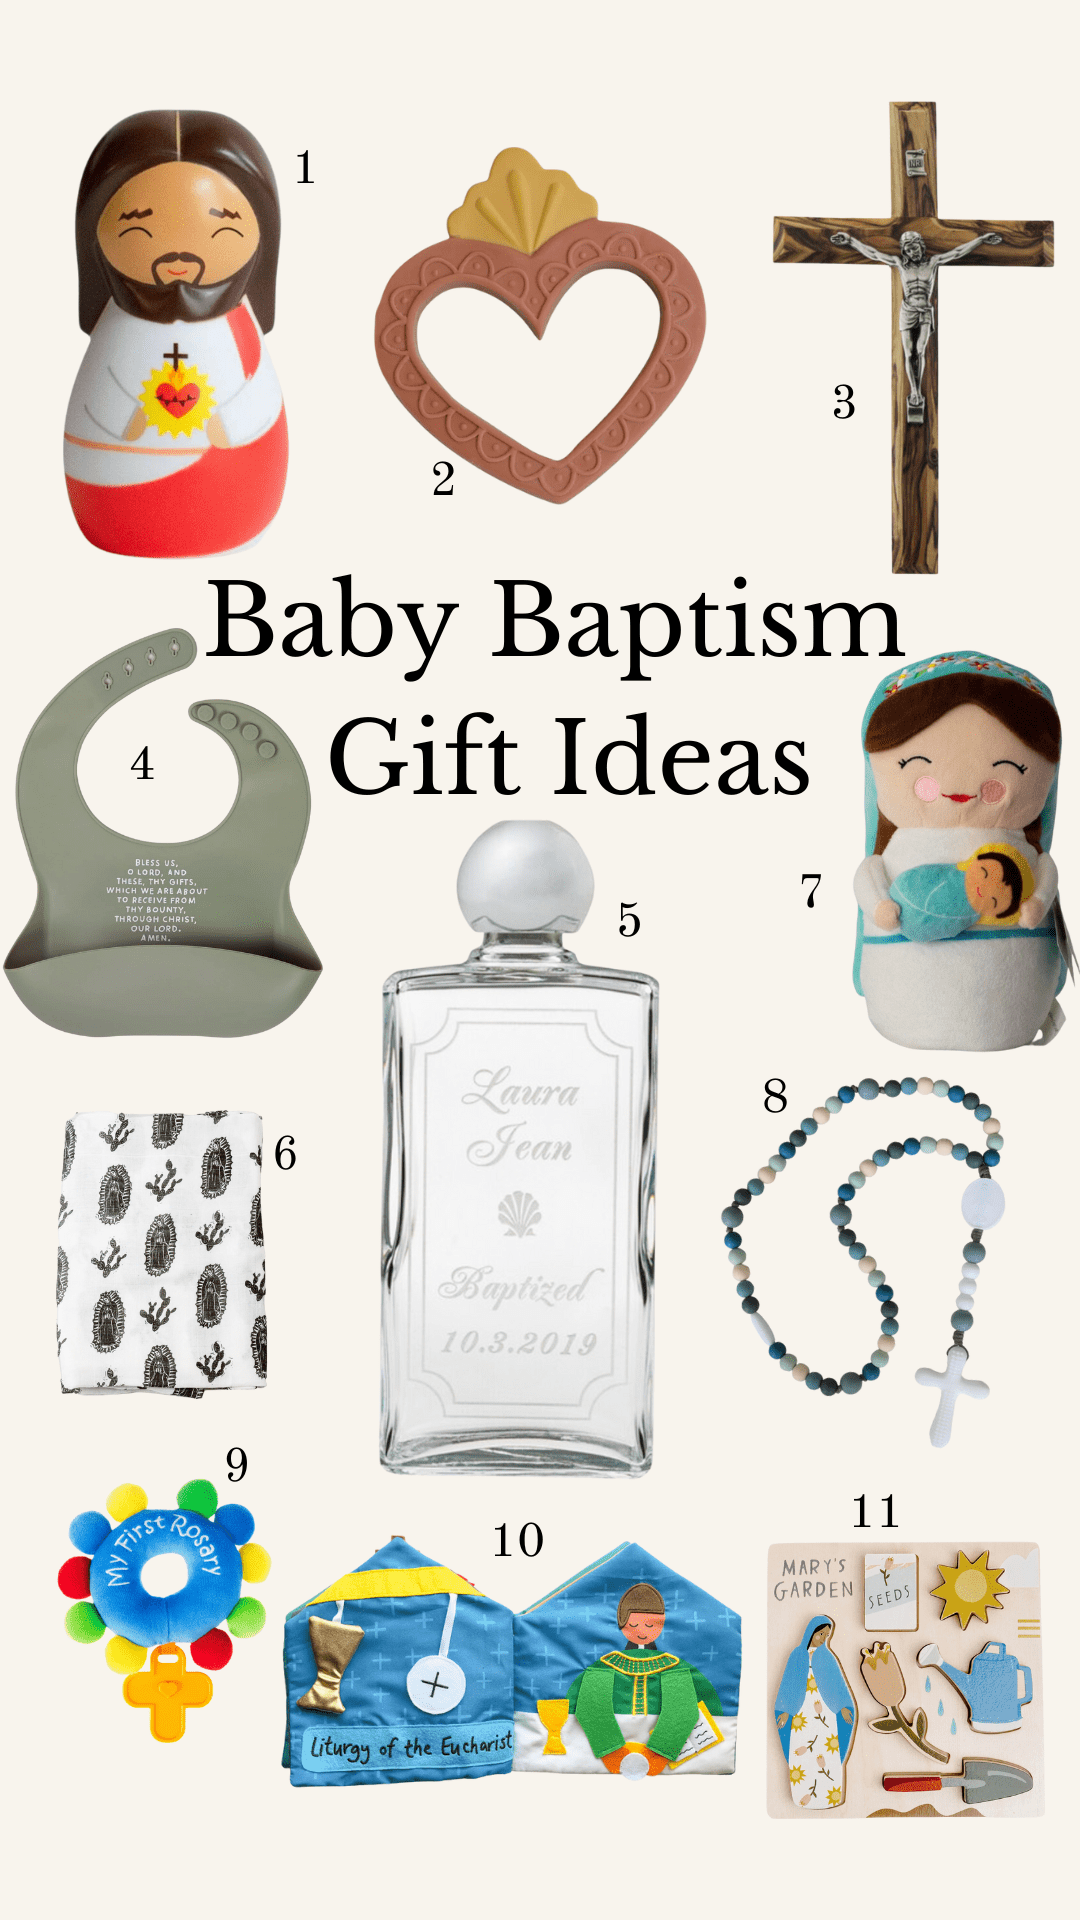
The Strategic Shift Toward Generational Wealth
The concept of generational wealth often feels like something reserved for the ultra-wealthy, but it begins with small, intentional actions. A baptism provides the perfect chronological “Year Zero” to implement a financial strategy. When we look at the trajectory of inflation and the rising costs of higher education and housing, it becomes clear that traditional trinkets, while beautiful, lack the capacity to support a child’s future self-sufficiency.
The Power of Compounding Interest
The primary reason to choose a financial gift at birth or baptism is the “time horizon.” Time is the most valuable asset in the world of investing. For a newborn, the investment horizon is roughly 18 to 25 years before they will likely need to access the funds for major life events.
If a godparent invests $2,000 in a diversified index fund at the time of a baptism and achieves a conservative 7% average annual return, that initial gift will grow to nearly $7,000 by the child’s 18th birthday—without any further contributions. If that gift is supplemented by small annual additions, the impact is exponential. By gifting financial assets, you are not just giving money; you are giving the child the benefit of two decades of market growth.
Moving Beyond Traditional Keepsakes
While a silver spoon is a classic symbol of prosperity, its value is largely static or tied to the spot price of precious metals. In contrast, a financial gift in the form of equities or educational savings is a “living” gift. It participates in the global economy and grows alongside the child. From a personal finance perspective, a gift that appreciates in value is a superior expression of care compared to a consumer good that depreciates or sits in a display case.
Strategic Investment Options for a Godchild’s Future
Selecting the right vehicle for a baptism gift requires an understanding of tax implications, control, and the intended use of the funds. There are several structures designed specifically for minors that offer significant advantages for the donor and the recipient.
Education Savings Plans (529 Plans)
In the United States, the 529 College Savings Plan is arguably the most powerful financial gift for a baptism. These plans allow for tax-advantaged growth and tax-free withdrawals, provided the funds are used for qualified education expenses. Given that the cost of tuition continues to outpace general inflation, a 529 plan is a pragmatic hedge against future debt.
One of the most attractive features of the 529 plan is its flexibility. If the child decides not to pursue traditional higher education, the SECURE 2.0 Act now allows for a lifetime maximum of $35,000 to be rolled over from a 529 plan into a Roth IRA for the beneficiary, subject to certain conditions. This means your baptism gift could literally jumpstart the child’s retirement savings if it isn’t needed for school.
Custodial Accounts (UGMA and UTMA)
For those who want to provide a gift that can be used for more than just education, Uniform Gifts to Minors Act (UGMA) and Uniform Transfers to Minors Act (UTMA) accounts are excellent choices. These are custodial accounts that allow an adult to manage assets for a minor until they reach the age of majority (usually 18 or 21, depending on the state).
The advantage of a UGMA/UTMA is that it can hold a wide variety of assets, including stocks, bonds, and mutual funds. This is a “no-strings-attached” financial foundation. However, donors should be aware that once the child reaches the age of majority, the assets become theirs to use as they wish. This makes these accounts a powerful tool for building a “launch fund” for a first home or a business venture.
High-Yield Savings Accounts (HYSA)
If the goal is to provide a liquid cash gift that still earns more than a traditional bank account, a High-Yield Savings Account (HYSA) is a low-risk entry point. While the returns may not match the stock market over 20 years, an HYSA offers safety and accessibility. This is often an ideal choice for smaller gifts or for families who prefer to maintain a “cash buffer” for the child’s immediate needs, such as extracurricular activities or early educational tools.
Hard Assets and Alternative Stores of Value
For some, the digital nature of a brokerage account feels too abstract for a baptism gift. In these cases, tangible assets that hold or increase in value over time offer a middle ground between traditional keepsakes and modern finance.
Gold and Precious Metals
Gold has been a standard for wealth preservation for millennia. Gifting a physical gold coin or a small bullion bar for a baptism is a way to provide “hard money” that the child can hold. Unlike currency, which can be devalued through inflation, gold maintains purchasing power over long periods. From a personal finance standpoint, this serves as a diversification tool. It teaches the recipient about the intrinsic value of commodities and provides a “break glass in case of emergency” asset that is independent of the banking system.
Cryptocurrency and Digital Assets
For the tech-forward donor, gifting Bitcoin or Ethereum has become an increasingly popular baptism gift. This is a high-risk, high-reward strategy. By setting up a cold storage wallet for the child, a donor can provide exposure to a new asset class. Given the 18-year timeframe, even a small amount of a “blue-chip” digital asset could potentially see massive appreciation. However, this should generally be a satellite gift rather than the core of the child’s financial portfolio due to its inherent volatility.
Premium Bonds and Government Securities
In some regions, government-backed savings bonds or premium bonds are a staple of baptism gifting. These are essentially loans made to the government that accrue interest over time. They are considered one of the safest investments available. While they may not offer the explosive growth of the S&P 500, they provide a guaranteed floor for the child’s future wealth. They are a “set it and forget it” gift that ensures the principal investment is protected.
Integrating Financial Literacy into the Gift
The greatest value of a financial baptism gift isn’t just the dollar amount—it’s the opportunity to teach financial literacy. As the child grows, the gift becomes a tangible case study in how money works.
Starting the Conversation Early
When a child reaches an age where they can understand basic math, the existence of their “baptism fund” can be used to explain concepts like interest, dividends, and market cycles. Instead of a gift that is forgotten in a toy box, a brokerage account statement becomes a teaching tool. This prepares the child to manage wealth responsibly when they eventually gain control of the assets.
The “Matching” Strategy for Future Contributions
A baptism gift can also set a precedent for future birthdays and holidays. A donor might commit to a “matching” strategy, where they contribute a certain amount to the child’s investment account for every dollar the child saves from their own allowance or part-time job later in life. This incentivizes a culture of saving and investing within the family, turning a one-time baptism gift into a lifelong behavioral shift.
Practical Considerations for Donors and Parents
Before finalizing a financial gift for a baptism, there are several logistical and tax-related factors to consider to ensure the gift is as efficient as possible.
Tax Implications and Gift Limits
In many jurisdictions, there are annual exclusion limits for gifts. In the United States, for instance, an individual can gift up to a certain amount per year (currently $18,000 as of 2024) to another person without having to file a gift tax return. For large baptism gifts, it is important to stay within these bounds or coordinate with a tax professional to understand how it affects the donor’s lifetime gift tax exemption.
Furthermore, the “Kiddie Tax” rules may apply to unearned income generated within custodial accounts. Understanding these thresholds ensures that the gift doesn’t create an unexpected tax burden for the parents.

Coordination with Family Financial Goals
A financial gift should ideally complement the parents’ existing plans for the child. If the parents have already established a 529 plan, it may be more beneficial to contribute directly to that existing account rather than opening a new one. Open communication ensures that the child’s portfolio is diversified and that all family members are working toward a cohesive financial future for the recipient.
Ultimately, what to give as a gift for a baptism is a question of legacy. By choosing a financial instrument, you are providing the child with something far more valuable than a physical object: you are providing them with options, security, and the freedom to pursue their dreams without the weight of financial scarcity. In the landscape of modern gift-giving, the gift of compounded growth is the most enduring blessing one can offer.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.