
Deciding to undergo a surgical procedure to stop menstruation is a significant medical step, but it is equally a major financial decision. Whether driven by medical necessity—such as endometriosis, heavy menstrual bleeding (menorrhagia), or fibroids—or by a personal choice to improve quality of life, understanding the economic landscape of these procedures is essential. In the realm of personal finance and healthcare management, the question “what surgery stops periods” must be answered not just with clinical definitions, but with a deep dive into market costs, insurance navigation, and the long-term return on investment (ROI) for the patient.
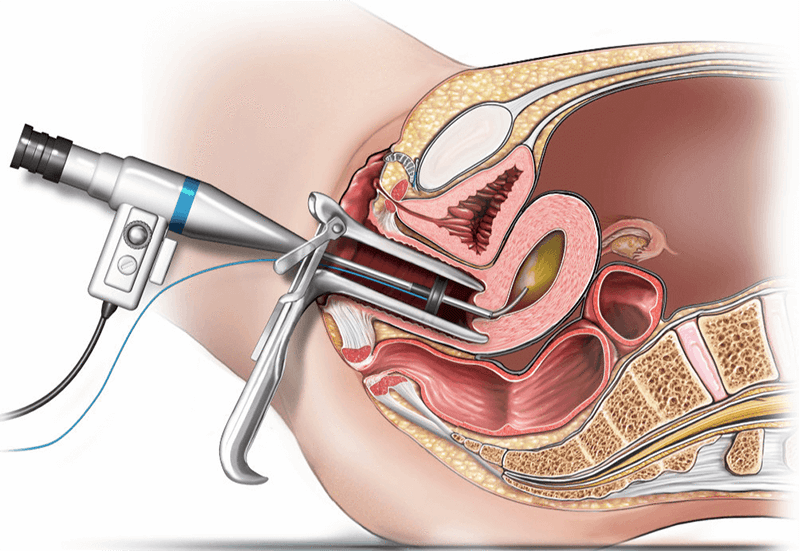
The two primary surgical interventions that result in the cessation of periods are endometrial ablation and hysterectomy. Each carries a vastly different price tag, recovery timeline, and insurance profile. By treating these procedures as a health investment, individuals can better navigate the complexities of the modern medical billing system while ensuring their physical and financial well-being.
Evaluating the Cost-Benefit Analysis of Permanent Period Suppression
When evaluating the financial impact of gynecological surgery, one must look beyond the immediate hospital bill. A comprehensive cost-benefit analysis includes the direct costs of the surgery, the indirect costs of recovery, and the long-term savings realized by the elimination of menstrual-related expenses.
The Price Tag of Endometrial Ablation vs. Hysterectomy
Endometrial ablation is often the first surgical consideration for those seeking to stop or significantly reduce their periods without a total organ removal. This procedure involves destroying the thin layer of the lining of the uterus (the endometrium). Financially, ablation is generally categorized as a “minor” surgery, often performed in an outpatient setting or even a well-equipped physician’s office. The national average cost for endometrial ablation ranges from $3,000 to $6,000. Because it does not require an overnight hospital stay and uses less intensive anesthesia, the facility fees remain relatively low.
In contrast, a hysterectomy—the complete removal of the uterus—is a major surgical undertaking. Depending on whether it is performed laparoscopically, robotically, or through traditional abdominal incision, the costs can escalate quickly. Market rates for a hysterectomy typically fall between $10,000 and $25,000. This higher price point accounts for operating room time, the presence of specialized surgical teams (including anesthesiologists), and potentially a multi-day hospital stay. From a financial planning perspective, a hysterectomy requires a much larger “sinking fund” or more robust insurance coverage than an ablation.
Factoring in Long-Term Savings on Menstrual Products
While the upfront cost of surgery is high, the long-term financial “break-even” point is an interesting metric for many patients. The average person who menstruates spends between $15 and $30 per month on tampons, pads, and liners. Over a decade, this totals $1,800 to $3,600. When you add the cost of pain relief medication, ruined clothing or bedding, and specialized skin care or heating pads, the annual expenditure rises significantly.
For a patient in their late 20s or early 30s dealing with severe menorrhagia, the cumulative cost of another 15 to 20 years of menstruation can rival or exceed the cost of an endometrial ablation. While surgery is rarely performed solely for the purpose of saving money on pads, the elimination of these recurring monthly costs is a tangible financial benefit that offsets the initial investment over time.
Navigating Insurance Coverage and CPT Codes
In the United States, the difference between a $20,000 bill and a $200 co-pay lies entirely in how the procedure is coded and whether it meets the insurer’s criteria for medical necessity. Understanding the language of insurance is a critical financial skill for anyone seeking surgery to stop their periods.
Medical Necessity vs. Elective Designations
Most insurance providers will not cover “period suppression” if it is categorized as purely elective for lifestyle convenience. However, if the periods are causing anemia, severe pain, or interfering with daily life (documented as “quality of life impairment”), the surgery is typically classified as medically necessary.
To ensure coverage, patients must work with their surgical team to document a history of “failed conservative management.” This usually means showing that the patient tried hormonal birth control, IUDs, or anti-inflammatory medications without success. From a financial strategy standpoint, maintaining a detailed “paper trail” of medical consultations and pharmacy receipts is vital. This documentation serves as the evidence required to move the procedure from “denied” to “covered” status.
Managing High Deductibles and Out-of-Pocket Maximums
For those on High Deductible Health Plans (HDHPs), the timing of the surgery can result in thousands of dollars in savings. Since a hysterectomy or ablation will likely meet the annual deductible in a single day, it is often financially advantageous to schedule the surgery early in the plan year if you expect to have other medical needs, or at the very end of the year if you have already hit your deductible through other treatments.
Furthermore, patients should be aware of “Current Procedural Terminology” (CPT) codes. For example, CPT code 58558 is commonly used for hysteroscopy with endometrial ablation. Knowing these codes allows the patient to call their insurer beforehand and get a precise “Explanation of Benefits” (EOB). This transparency prevents the “sticker shock” of unexpected facility fees or out-of-network anesthesiology charges that often plague hospital billing.

Financial Tools for Medical Procedures: HSAs and FSAs
The American tax code provides several vehicles that can significantly reduce the effective cost of surgery. Leveraging these accounts is a hallmark of savvy personal finance management.
Leveraging Pre-Tax Dollars for Surgical Expenses
Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs) allow individuals to set aside pre-tax income for qualified medical expenses. If a patient is in the 24% tax bracket, using an HSA to pay for a $5,000 ablation essentially provides a 24% discount compared to paying with post-tax “take-home” pay.
For a hysterectomy, which may require hitting an out-of-pocket maximum of $7,000 or more, the tax savings can exceed $1,500. Patients planning for these surgeries should maximize their contributions during the enrollment period preceding their surgery date. Because HSA funds roll over year-to-year, they act as a “medical IRA,” providing a tax-advantaged way to build a surgical fund over several years.
Payment Plans and Medical Financing Strategies
If insurance coverage is partial or if the deductible is out of reach, many medical institutions offer internal financing. Zero-percent interest payment plans are common in large hospital systems, as they would rather receive steady payments than send a bill to collections.
Additionally, specialized medical credit cards or personal loans can be utilized, though these should be approached with caution. The interest rates on medical credit cards can jump significantly if the balance isn’t paid within the promotional period. A better financial move is often negotiating the “cash price” with the provider. Many hospitals offer a 10% to 30% discount for bills paid in full upfront, which can be cheaper than financing the procedure over time.
The Economic Impact of Surgical Recovery and Career Productivity
The “true cost” of a surgery includes the time spent away from work. This is an opportunity cost that varies wildly depending on the type of procedure chosen and the patient’s employment structure.
Short-Term Disability and Paid Leave Considerations
An endometrial ablation typically requires only 24 to 48 hours of recovery time, meaning most employees can schedule it on a Friday and return to work on Monday. The impact on income is minimal. A hysterectomy, however, generally requires six to eight weeks of recovery.
For those in the corporate world, this necessitates a deep dive into the employer’s Short-Term Disability (STD) policy. Most STD policies pay between 60% and 100% of a salary after a one-week “elimination period.” For freelancers or “gig economy” workers, an eight-week absence from work represents a massive hit to gross income. In these cases, the financial decision-making process must include a “recovery fund” to cover rent, utilities, and groceries while the patient is unable to generate revenue.
Hidden Costs: Childcare and Home Recovery Expenses
Recovery from major surgery involves physical limitations, such as “lifting restrictions,” which prevent a patient from picking up a child or performing heavy housework. From a budgeting perspective, one must account for the “hidden” costs of recovery:
- Childcare: If the patient is a primary caregiver, hiring help for several weeks may be necessary.
- Home Services: Grocery delivery fees or a temporary cleaning service to handle chores during the recovery window.
- Medical Supplies: Post-operative garments, prescriptions, and specialized nutrition.
When these costs are tallied, the financial footprint of a hysterectomy may be 20% higher than the hospital bill alone. Proper financial planning involves identifying these gaps before the surgery date to ensure that the recovery process does not lead to high-interest consumer debt.
Conclusion: The Long-Term ROI of Health
In the world of finance, we often talk about “investing in yourself.” Surgical procedures that stop debilitating periods are a prime example of an investment in human capital. By eliminating chronic pain, anemia-induced fatigue, and the monthly financial drain of menstrual management, many patients find that their career productivity and overall life satisfaction increase.
From a purely monetary perspective, the transition from a “period-heavy” life to one without menstruation is a move toward efficiency. While the upfront costs are significant—ranging from a few thousand to tens of thousands of dollars—the combination of tax-advantaged savings (HSAs), strategic insurance navigation, and the elimination of recurring costs creates a compelling financial case. When you answer “what surgery stops periods,” you are not just choosing a medical path; you are making a calculated decision to reallocate your financial resources toward a future of improved health and long-term economic stability.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.