
For the modern investor or financially conscious parent, the arrival of a new family member marks the beginning of a complex series of micro-economic decisions. While the surface-level question “what size shoe does a 4-month-old wear?” seems like a simple matter of physical measurement, it actually represents a fascinating entry point into the unit economics of infant apparel and the broader financial management of early childhood expenses. In the world of personal finance and household budgeting, understanding the lifecycle of high-turnover assets—such as infant footwear—is essential for maintaining a healthy bottom line during the high-cost years of early parenting.
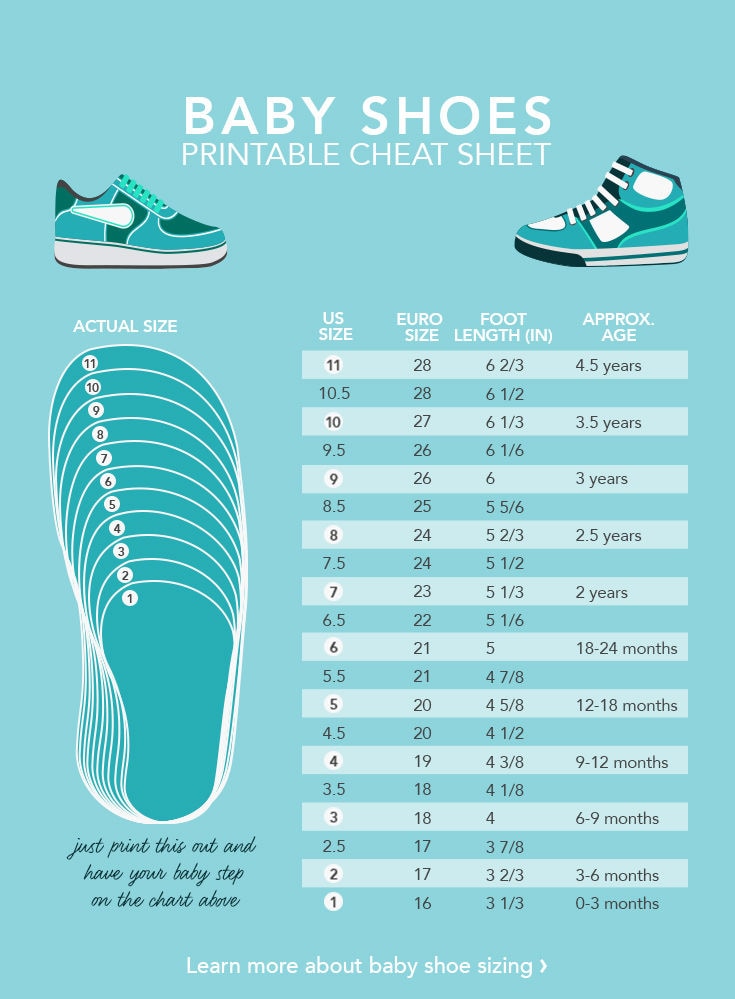
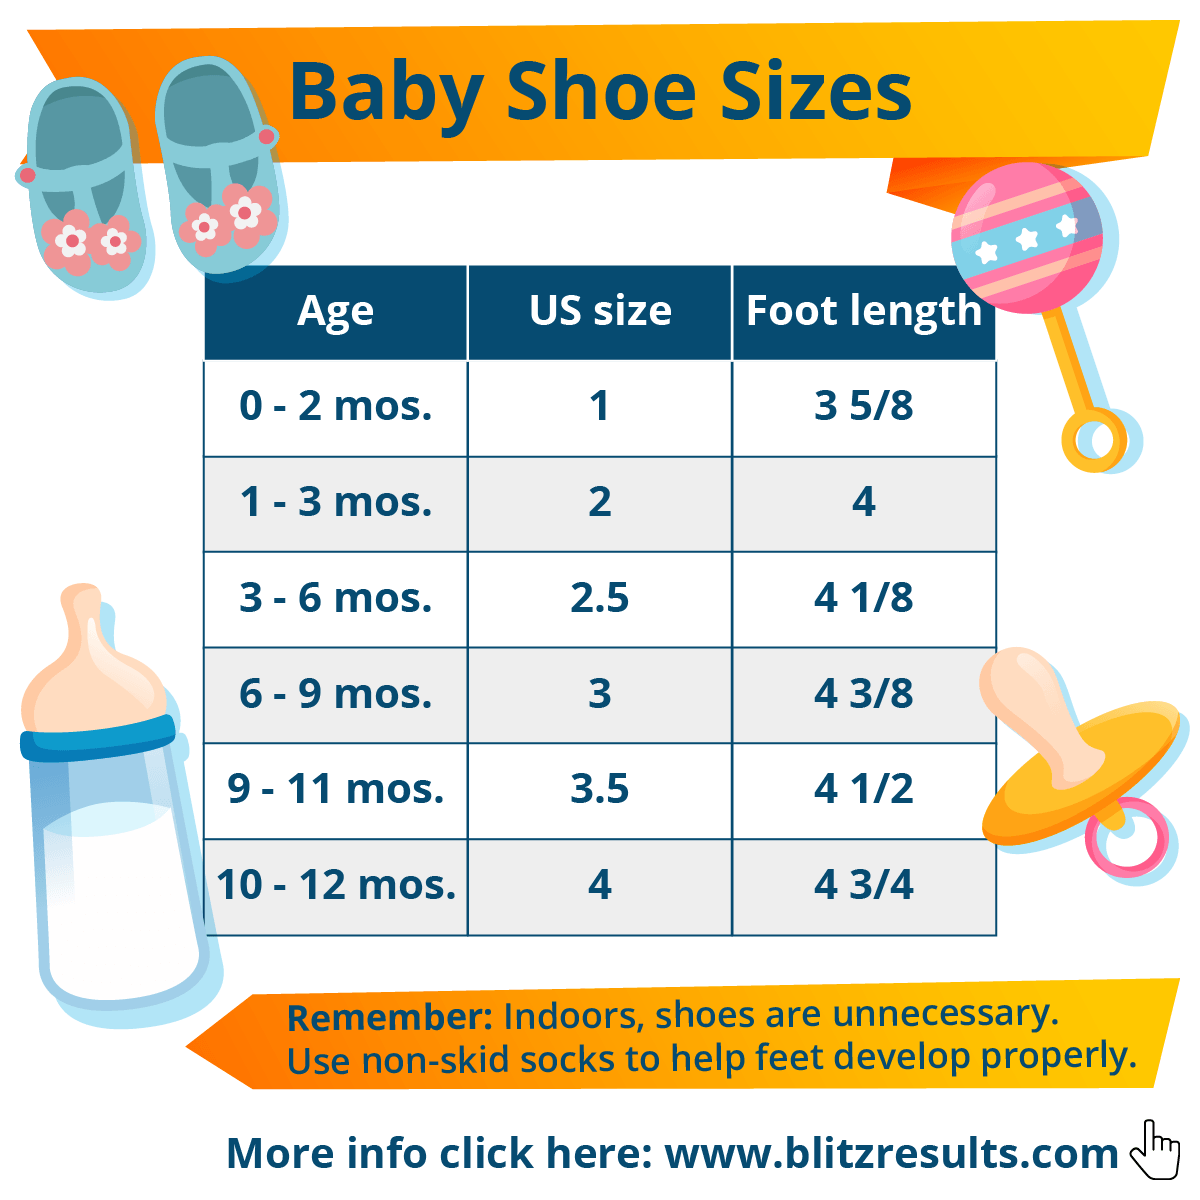
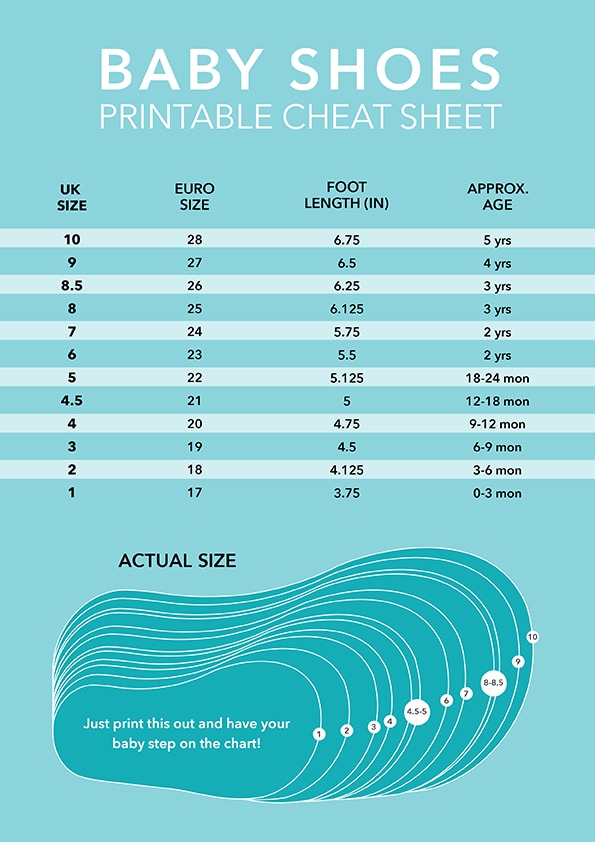
Typically, a 4-month-old infant will wear a US size 1 or 2 (which corresponds to an age range of zero to six months). However, in the realm of financial planning, the “size” of the shoe is less important than the “utility” and the “cost per wear” (CPW). At four months, most infants are not yet cruising or walking, meaning footwear serves a primary function of thermal regulation and a secondary function of aesthetic branding. For the fiscally responsible household, this stage represents a critical juncture where emotional spending often clashes with rational asset allocation.
The Financial Landscape of Infant Footwear
The infant apparel market is a multi-billion dollar global industry designed to capitalize on the rapid growth cycles of children. For a 4-month-old, the growth rate is at its peak velocity. From a financial perspective, purchasing high-end footwear for an infant in this age bracket is akin to investing in a highly volatile, rapidly depreciating asset.
Understanding the High-Frequency Consumption Cycle
The primary challenge in managing a budget for a 4-month-old is the frequency of replacement. Because infants grow at an exponential rate during the first year, a pair of shoes may only fit for four to eight weeks. This creates a high-frequency consumption cycle that can drain a liquid savings account if not managed with a corporate-style procurement mindset.
When we analyze the transition from size 1 to size 2, we are looking at a timeframe where the physical utility of the item is minimal. Unlike adult footwear, which may provide utility for 500 to 1,000 miles of walking, infant footwear at the 4-month mark provides almost zero functional “mileage.” Therefore, the financial logic dictates that capital should be preserved for the stages where footwear becomes a functional necessity for mobility and safety.
The Cost per Wear (CPW) Metric for Infants
To truly understand the impact of infant shoe sizes on a household budget, one must apply the Cost per Wear (CPW) formula: Total Cost of the Item divided by the Number of Times Worn.
Consider a premium designer infant shoe costing $60. If a 4-month-old wears these shoes twice a week for six weeks before outgrowing them, the CPW is $5 per wear. Compare this to a $10 budget option or a high-quality second-hand acquisition at $5, where the CPW drops to roughly $0.41. Over the course of the first 24 months of a child’s life, these micro-decisions aggregate into thousands of dollars in potential savings or expenditures.
Market Volatility in Sizing: Why Standardization Affects Your Budget
One of the greatest inefficiencies in the infant footwear market is the lack of universal sizing standards. Just as stock market volatility can lead to poor investment timing, “sizing volatility” can lead to wasted capital. A size 2 in one brand may be physically smaller than a size 1 in another. This lack of standardization forces parents into a cycle of over-purchasing to ensure a fit, leading to an “inventory surplus” of unworn shoes.
Brand Variance and Price Premium
High-end brands often use proprietary sizing charts to create a sense of exclusivity and “brand lock-in.” When a parent finds a brand that fits their 4-month-old perfectly, they are more likely to stay with that brand through subsequent sizes, even if the price premium is 200% above market average.
From a brand strategy perspective, these companies are not selling shoes; they are selling a lifestyle and a sense of security. However, from a financial perspective, the price premium for a 4-month-old’s shoe—where the construction requires minimal material and no advanced ergonomic support—is often unjustifiable. The markup on infant “soft-sole” shoes is among the highest in the retail apparel sector.
The Myth of “Investment” Pieces in Early Infancy
In the luxury resale market, certain items are marketed as “investment pieces.” While this may hold true for high-end watches or certain designer handbags, it rarely applies to infant footwear. The 4-month-old size bracket (Size 1-2) is the most saturated segment of the second-hand market because the items are outgrown before they can show any signs of wear.
Investors in this space—namely, parents looking to recoup costs—should be aware that the resale value of infant shoes drops by 60-80% the moment they are removed from the packaging. The liquidity of these assets is low, making them a poor “investment” in any traditional sense.
Strategic Purchasing: Maximizing Value for a 4-Month-Old
To navigate the financial demands of a growing infant, households must adopt strategic purchasing habits that mirror supply chain management. By treating the nursery as a small business with recurring inventory needs, parents can optimize their cash flow.
Second-Hand Market Dynamics and Resale Value
The most sophisticated financial move for sourcing shoes for a 4-month-old is to tap into the secondary market. Because 4-month-olds do not walk, their shoes are almost always in “New Without Tags” (NWOT) or “Excellent Pre-Owned Condition” (EUC).
Platforms like Poshmark, Mercari, and local consignment shops are overflowing with size 1 and 2 shoes that have been worn for a single photo shoot or a family event. By purchasing these items at 20 cents on the dollar, a family can maintain their aesthetic standards while diverting the remaining 80% of the capital into a 529 College Savings Plan or an index fund. The compounding interest on $40 saved on a pair of shoes today can grow into thousands by the time the child reaches university age.
Bulk Purchasing vs. Just-in-Time Inventory
In business, “Just-in-Time” (JIT) inventory management minimizes the amount of capital tied up in stock. For infant shoes, however, a hybrid approach is often more cost-effective. Buying the next two sizes (Size 2 and Size 3) during end-of-season clearance sales can result in savings of 50-70%.
The risk of JIT purchasing for a 4-month-old is that when the child suddenly hits a growth spurt and jumps to the next size, the parent may be forced to pay full retail price at a local store due to immediate need. Maintaining a small “buffer stock” of the next size up—acquired at a discount—is a hedge against retail price inflation.
Beyond the Basics: Long-Term Financial Planning for Childcare Costs
The question of shoe size is ultimately a microcosm of the larger financial journey of parenthood. If a household struggles to manage the budget for size 2 shoes, the larger capital expenditures of the future—private schooling, extracurricular activities, and healthcare—will be even more daunting.
Clothing as a Recurring Operating Expense
In a corporate P&L statement, certain costs are “one-time,” while others are “operating expenses.” Infant clothing and footwear should be classified as a recurring operating expense. By setting a fixed monthly “shoe and apparel” budget, parents can avoid the “lifestyle creep” that often accompanies the arrival of a new child.
Whether the 4-month-old needs a size 1 or a size 2, the financial commitment remains consistent. Budgeting for these transitions allows for better “cash flow forecasting.” If you know your child will likely move through four shoe sizes in their first year, you can allocate those funds in January rather than being surprised by the expense in June.
Tax Implications and Flexible Spending Accounts
For those in higher tax brackets, utilizing a Dependent Care Flexible Spending Account (FSA) or understanding the tax credits associated with child-rearing can offset the general costs of infant care, providing more liquidity for daily necessities like footwear. While shoes themselves are not usually tax-deductible, the overall management of “child-related capital” requires a holistic view of the family’s tax position.
By the time a child reaches the 4-month mark, the initial “startup costs” of the nursery have usually stabilized, and the “operational phase” begins. This is the perfect time to audit spending habits. Are you buying shoes for your 4-month-old to fulfill a functional need, or are you succumbing to “competitive parenting” consumption?
In conclusion, while a 4-month-old typically wears a size 1 or 2, the savvy financial manager looks beyond the number. They see a short-term asset with high depreciation and low functional utility. By applying rigorous financial principles—CPW analysis, secondary market procurement, and strategic inventory management—parents can ensure that their child is well-outfitted without compromising the family’s long-term financial security. Saving $30 on a pair of size 2 shoes might seem insignificant in isolation, but in the grand scheme of a twenty-year financial plan, these disciplined choices are the foundation of generational wealth.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.