
In the world of personal finance, much like in dental care, the secret to long-term success is not found in a single, heroic act, but in the disciplined execution of a daily routine. We often hear the terms “financial health” or “fiscal fitness,” but perhaps the most accurate metaphor is “financial hygiene.” Just as neglecting your teeth leads to painful cavities and expensive root canals, neglecting your daily financial habits leads to high-interest debt, missed opportunities, and a retirement that arrives far too late.
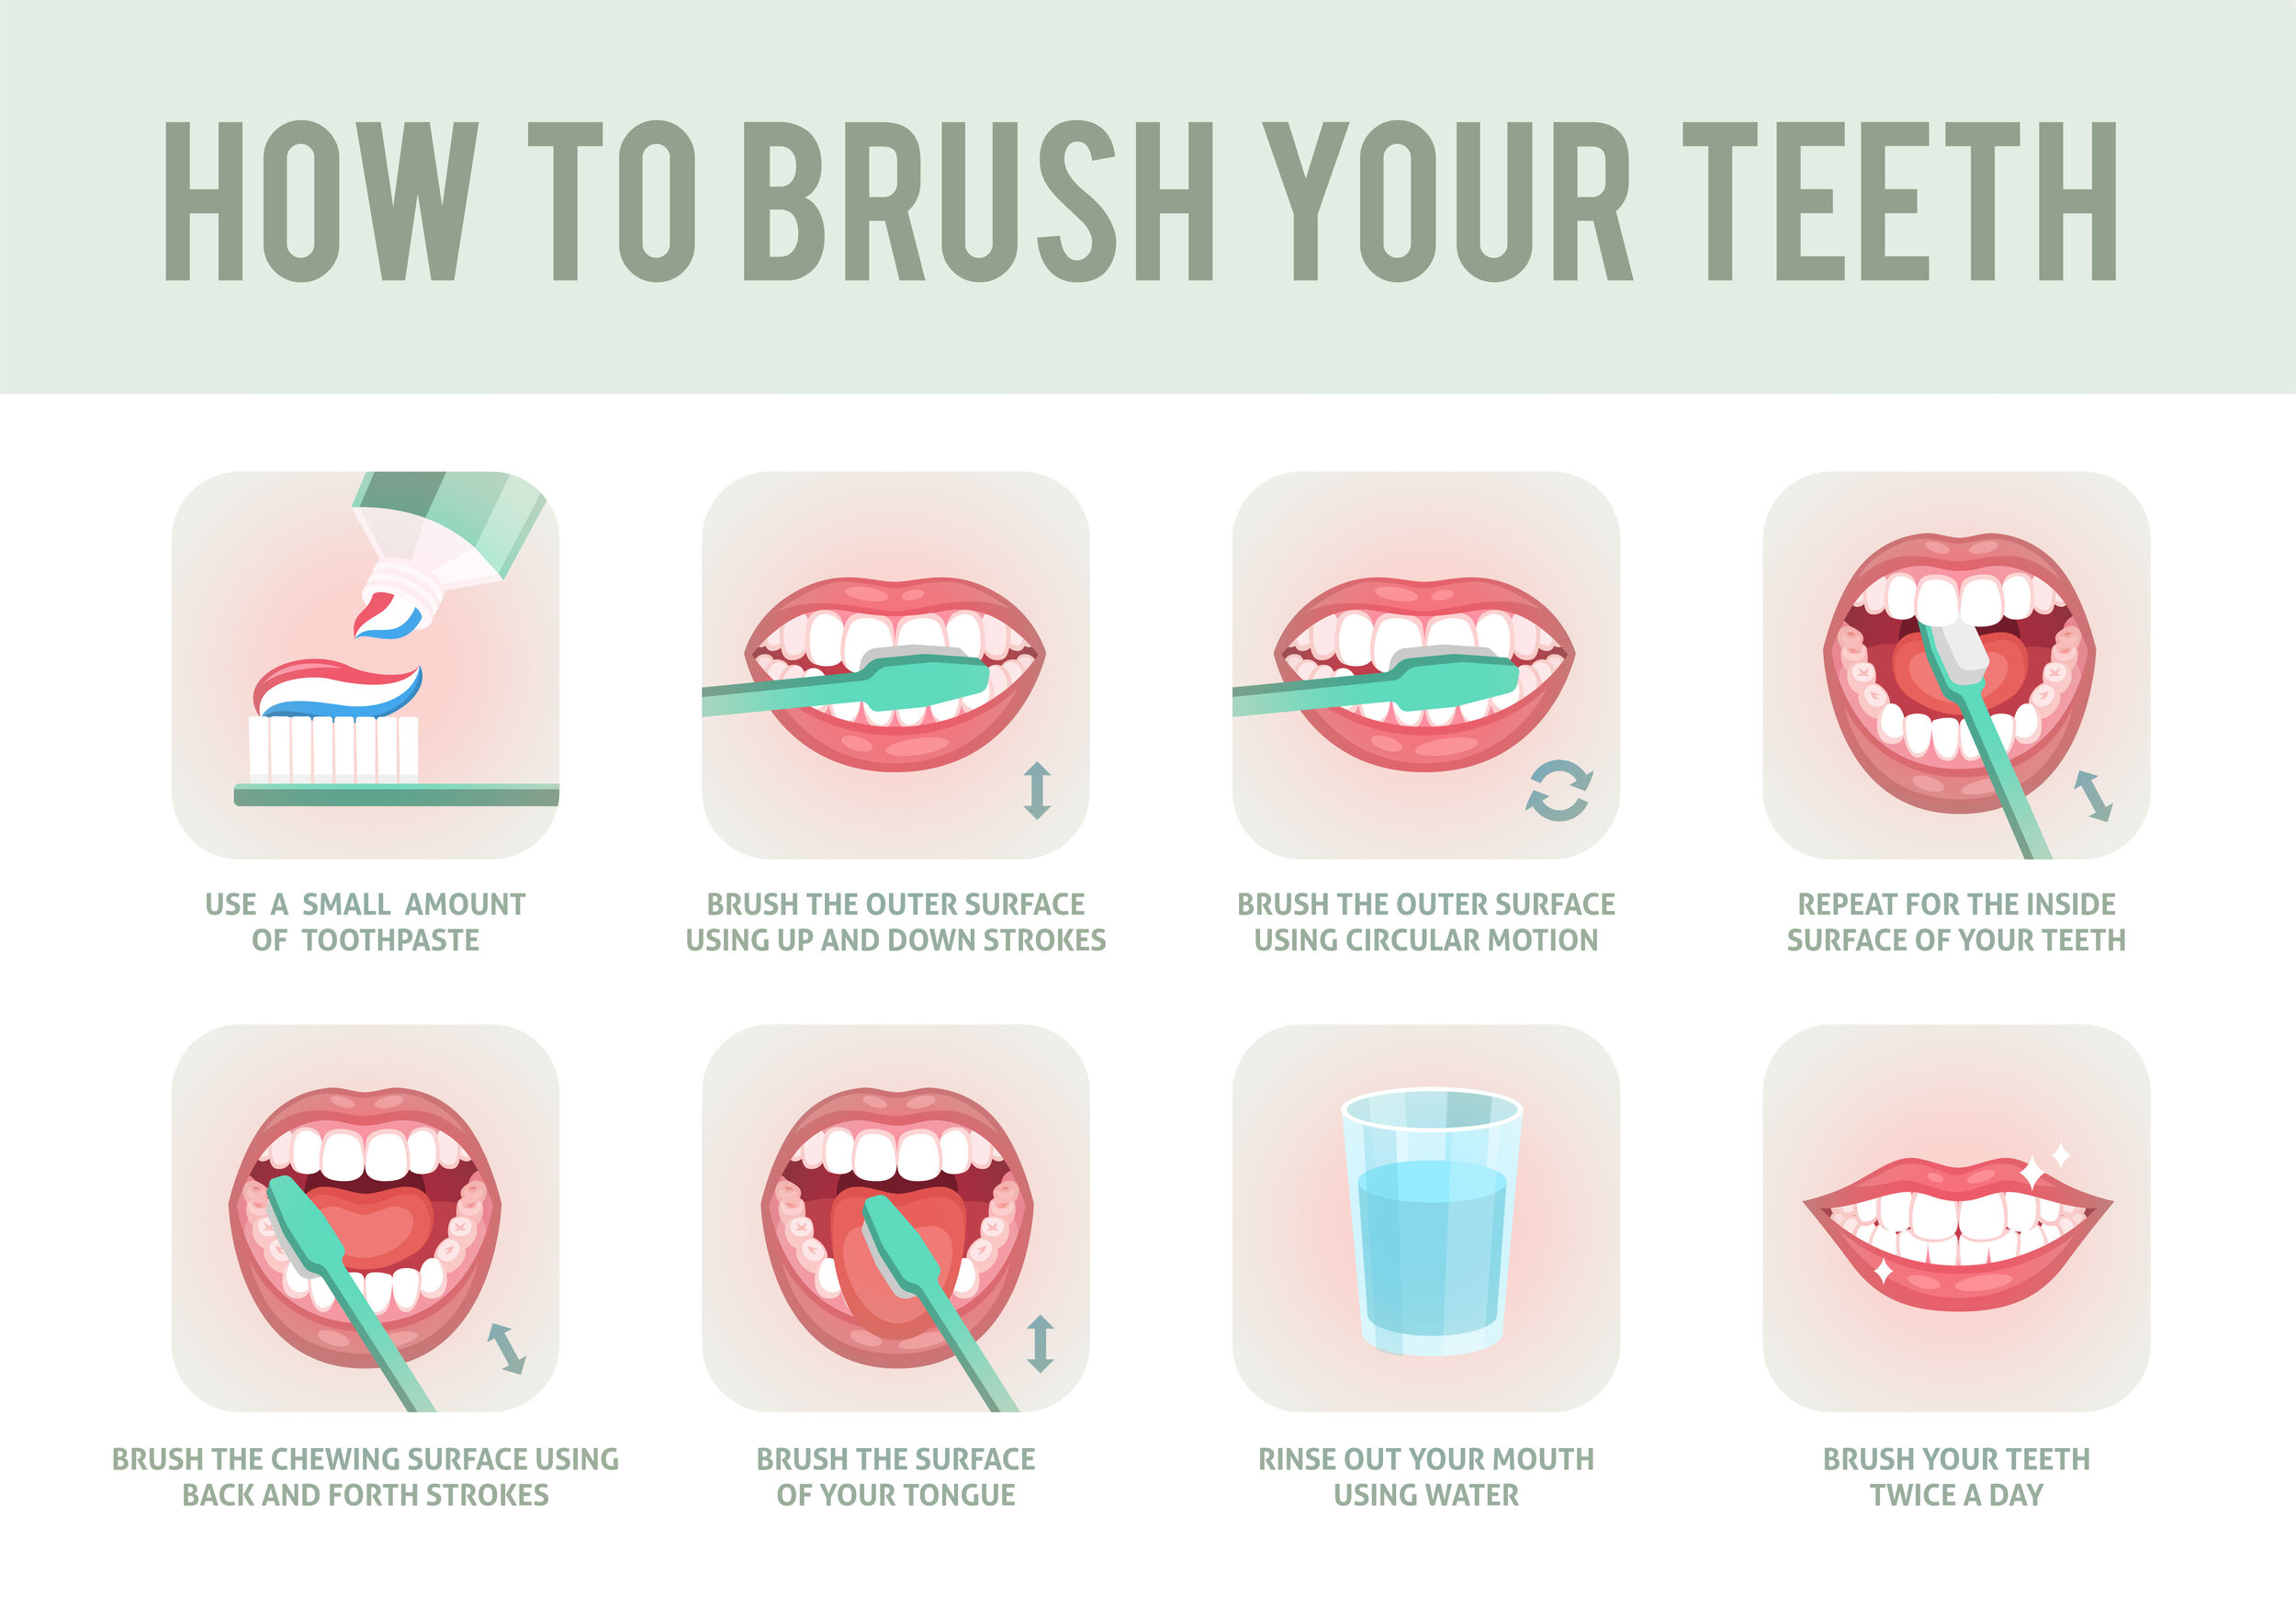
The question of sequence—what is the proper order for brushing, flossing, and rinsing—is a common debate in the dental world. When applied to the architecture of your money, this sequence becomes a roadmap for wealth accumulation. In a financial context, “brushing” represents the daily maintenance of budgeting and tracking, “flossing” represents the deep work of debt management and credit optimization, and “rinsing” represents the final, protective layer of investing and portfolio rebalancing. Understanding the proper order of these actions is the difference between a cluttered ledger and a flourishing net worth.
Establishing the Foundation: Daily Brushing (Budgeting and Tracking)
Brushing is the most fundamental aspect of oral hygiene. It is the surface-level cleaning that happens twice a day to prevent the buildup of plaque. In the realm of personal finance, brushing is your daily interaction with your budget. It is the act of tracking expenses, monitoring cash flow, and ensuring that your spending aligns with your values. Without this foundational step, any other financial strategy—no matter how sophisticated—will eventually fail.
The Consistency of Expense Tracking
Most people treat budgeting as a monthly chore, a grueling session of “financial flossing” where they look back at thirty days of mistakes. However, true financial brushing must be a daily habit. In the modern economy, “micro-leaks” are the greatest threat to wealth. These are the small, frictionless transactions—the $6 lattes, the $15 app subscriptions, and the $20 convenience fees—that slip through the cracks of a monthly review.
When you “brush” your finances daily by checking your accounts and logging transactions, you develop a “wealth consciousness.” You begin to see the direct correlation between your daily choices and your long-term goals. This isn’t about deprivation; it’s about awareness. Just as brushing removes the day’s debris before it hardens into tartar, daily tracking removes the impulse to spend mindlessly before it hardens into a lifestyle that your income cannot support.
Automation as the Electric Toothbrush of Finance
Just as an electric toothbrush provides a more thorough and consistent clean than manual brushing, automation is the ultimate tool for financial hygiene. Many individuals struggle with the discipline required to manually move money into savings or pay bills on time. By automating your financial “brushing,” you remove human error from the equation.
Set up automatic transfers to your “emergency fund” the same day your paycheck hits. Automate your utility payments and credit card minimums to avoid late fees—the financial equivalent of gingivitis. When your foundational movements are automated, you ensure a baseline level of health even during weeks when you are too busy to look at your spreadsheets. This allows you to maintain a clean slate, ready for the deeper work of wealth building.
The Deep Clean: Flossing the Gaps (Debt Management and Credit Optimization)
If brushing is about the surface, flossing is about getting into the tight spaces where the real damage occurs. In your financial life, “flossing” is the aggressive management of debt and the optimization of your credit profile. You can brush your teeth perfectly every day, but if you never floss, you will still end up with cavities between your teeth. Similarly, you can have a perfect budget, but if you are carrying 24% interest on a credit card, your financial health is at risk.
Reaching the Hidden Decay of High-Interest Debt
High-interest debt is the “decay” of the financial world. It eats away at your future earnings and prevents your capital from working for you. The proper order of financial hygiene dictates that you must address these gaps before you move on to the “rinsing” stage of aggressive investing.
There are two primary methods for financial flossing: the Debt Snowball and the Debt Avalanche. The Snowball method focuses on psychological wins by paying off the smallest balances first, providing the momentum needed to stay the course. The Avalanche method focuses on mathematical efficiency by targeting the highest interest rates first. Regardless of the method, the goal is the same: to clear the debris from the hidden corners of your balance sheet. This “flossing” requires more effort and discomfort than daily brushing, but it is the only way to ensure that the foundation of your house is not rotting from within.
Strengthening the Gums: Building a Credit Profile
Flossing doesn’t just remove food; it strengthens the gums. In finance, managing your debt is only half the battle; the other half is optimizing your credit score. Your credit score is the “gum health” of your financial mouth—it supports everything else. A strong credit profile allows you to access lower interest rates on mortgages and insurance, effectively “lowering the cost” of your life.
To optimize this area, you must look at credit utilization ratios and the age of your accounts. This deep-dive work ensures that when you are ready to make a major move—such as buying a home or starting a business—your financial structure is strong enough to support the weight. Neglecting this stage while focusing only on “rinsing” (investing) is a common mistake that leads to structural failure when the market shifts or life emergencies arise.
The Finishing Touch: Rinsing for Long-Term Health (Investing and Rebalancing)
In oral hygiene, rinsing with a fluoride or antiseptic wash is the final step. It coats the teeth, kills remaining bacteria, and provides a protective layer that lasts throughout the day. In finance, “rinsing” is the act of investing and portfolio rebalancing. It is the final stage that takes a “clean” financial life and makes it a “prosperous” one.
Diversification: The Antiseptic for Market Volatility
If you rinse before you brush, you are simply washing over the dirt. This is why investing (rinsing) should generally follow the establishment of a budget (brushing) and the elimination of high-interest debt (flossing). Once those stages are complete, you can begin the process of long-term wealth protection.
Diversification is the ultimate antiseptic for a portfolio. By spreading your assets across various classes—equities, bonds, real estate, and perhaps alternative assets—you protect yourself against the “bacteria” of market volatility. A well-rinsed financial plan doesn’t just aim for growth; it aims for resilience. It ensures that even if one sector of the economy suffers, the overall health of your net worth remains intact.
Periodic Rebalancing and Tax-Loss Harvesting
A rinse is not a one-time event; it is a regular part of the routine. In the investment world, this manifests as periodic rebalancing. Over time, certain assets will outperform others, causing your portfolio to become lopsided. A person who started with a 60/40 stock-to-bond ratio might find themselves at 80/20 after a bull market.
Rebalancing is the act of “rinsing” the portfolio to bring it back to its intended state. Furthermore, sophisticated financial hygiene includes “tax-loss harvesting”—the process of selling losing investments to offset capital gains taxes. This keeps your financial “mouth” fresh and efficient, ensuring that you aren’t losing wealth to unnecessary tax liabilities.
The Financial Checkup: Why the Order Matters
The question of “proper order” is not merely academic; it is functional. If you rinse with mouthwash before you brush, you are wasting the product on surface-level debris that would have been removed anyway. In finance, if you prioritize investing (rinsing) while you still have $20,000 in credit card debt at 22% interest (the need for flossing), you are mathematically sabotaging yourself. The 7-10% returns of the stock market cannot outrun the 22% decay of high-interest debt.
Why You Shouldn’t Rinse Before You Brush
Many young professionals make the mistake of jumping straight into “rinsing”—buying speculative cryptocurrencies or individual stocks—without ever establishing a “brushing” routine (a budget). Without a budget, you don’t know how much you can actually afford to lose. You risk “choking” on your investments because you haven’t cleared the airway of your monthly cash flow.
The proper order—Brushing, then Flossing, then Rinsing—ensures that every dollar you earn has a purpose and a place. It builds a hierarchy of needs that protects you from the most common financial pitfalls. Brushing gives you the data. Flossing gives you the freedom from debt. Rinsing gives you the growth that leads to generational wealth.

Scaling Your Financial Routine
As your income grows, your hygiene routine must scale accordingly. A simple manual toothbrush might work for a teenager, but a CEO with complex assets needs the “water flosser” and “professional cleaning” of specialized financial tools. This might include using high-yield savings accounts as a “pre-rinse” for your emergency fund or utilizing tax-advantaged accounts like a 401(k) or HSA as a “deep cleaning” mechanism.
The beauty of the Brushing-Flossing-Rinsing framework is its scalability. Whether you are earning $40,000 or $400,000, the sequence remains the same. You must track your output, manage your liabilities, and protect your assets. By maintaining this order, you ensure that your financial health is not a matter of luck, but a result of meticulous, daily care. In the end, wealth is not just about what you earn; it is about the hygiene you maintain with the money you keep.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.