
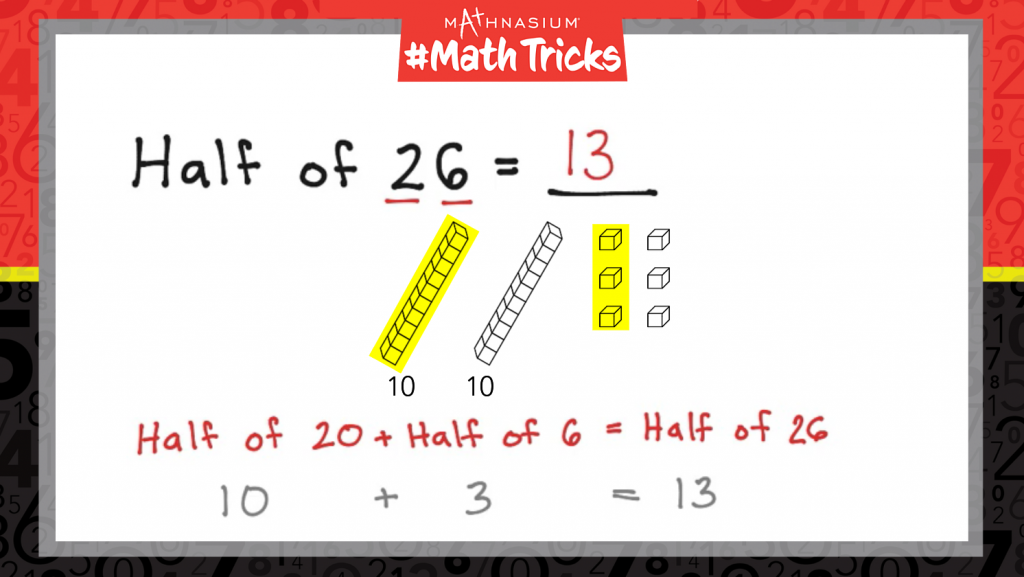
In the landscape of personal finance, certain ages serve as cultural and economic markers. While 18 signifies legal adulthood and 65 often heralds retirement, the age of 26 has emerged as a silent but critical “pivot point” for the modern professional. When we ask “what is half of 26,” the mathematical answer is 13, but the financial answer is much more complex. It represents the “Rule of 13″—a strategic approach to wealth building that dictates how one should manage the transition from youthful experimentation to serious asset accumulation.
At 26, the safety nets of the early twenties begin to dissolve. In many jurisdictions, this is the final year a young adult can remain on a parent’s health insurance plan. It is also often the stage where entry-level roles transition into mid-career positions, bringing a significant increase in disposable income. Understanding how to leverage “half of 26” is not just a math exercise; it is a blueprint for financial independence.
The Significance of the Age 26 Pivot
The age of 26 is widely considered the threshold of “true” financial independence. For most, the first half of their twenties is spent navigating the complexities of the labor market, often while burdened by student debt or entry-level wages. By the time an individual hits 26, they have typically acquired enough professional experience to command a higher market value. However, this increase in income often coincides with an increase in responsibility.
Navigating the Insurance Off-Ramp
One of the most immediate shifts at 26 is the requirement to manage one’s own risk. Transitioning to an independent health insurance plan is a significant budgetary milestone. This shift requires a deep understanding of premiums, deductibles, and Health Savings Accounts (HSAs). For the savvy 26-year-old, an HSA is not just a health tool; it is a triple-tax-advantaged investment vehicle. By contributing the maximum allowed to an HSA, you are effectively reducing your taxable income while building a portable fund for future medical expenses or retirement.
The Psychology of the Mid-Twenties
Psychologically, 26 is the year many individuals stop “playing house” with their finances and start building a foundation. This is the period where the “instant gratification” mindset of the early twenties battles with the “long-term security” mindset of the thirties. The most successful investors are those who can reconcile these two halves. They recognize that while they are only half of 26 (13) years away from being 39, the decisions made today will compound exponentially.
The Rule of 13: Why 13% is the Magic Savings Rate
If 26 is the pivot point, then 13%—exactly half of 26—is the target savings rate that can transform a standard career into a wealth-generating engine. While traditional financial advice often suggests a 10% savings rate, the modern economic environment (characterized by higher housing costs and inflation) demands a more aggressive stance. Aiming for 13% of gross income toward retirement and long-term investments creates a safety margin that 10% simply cannot provide.
The Math of Compounding at 26
To understand why 13% is the magic number at age 26, one must look at the time horizon. If an individual starts aggressively investing at 26, they have nearly 40 years of compounding before traditional retirement age. A 13% contribution rate, assuming a standard 7% annual return, puts an individual on a trajectory to reach “Coast FIRE” (the point where no more contributions are needed to reach a comfortable retirement) much faster than their peers.
Diversification Beyond the 401(k)
Achieving a 13% investment rate requires a sophisticated approach to asset allocation. It is no longer enough to simply contribute to an employer-sponsored 401(k). At 26, an individual should be looking at a “tax-bucket” strategy:
- Tax-Deferred: 401(k) or 403(b) to capture employer matches.
- Tax-Free: Roth IRA or Roth 401(k) to hedge against future tax increases.
- Taxable: Low-cost index funds in a standard brokerage account for liquidity before age 59.5.
By splitting your focus across these three buckets, you ensure that you have “half” of your assets growing in high-growth environments and the other half available for strategic pivots, such as purchasing real estate or starting a business.
Strategic Allocation: The 50/30/20 Rule for the 26-Year-Old

While the “Rule of 13” focuses on long-term growth, daily life at 26 requires a rigorous budgeting framework. The 50/30/20 rule is often cited, but at 26, it requires a specific nuance to be effective.
Needs vs. Wants in an Urban Economy
For many 26-year-olds, the “50%” allocated to needs (housing, utilities, groceries) is under siege by rising rents. To maintain a healthy financial profile, it is vital to keep housing costs to no more than 25-30% of take-home pay. This may mean choosing to live with roommates or in a less “trendy” neighborhood for a few more years. The “half of 26” philosophy suggests that by sacrificing 13% of your “lifestyle” today, you gain 100% of your freedom tomorrow.
The Role of the Emergency Fund
At 26, an emergency fund is non-negotiable. This fund should cover at least three to six months of essential expenses. In a volatile job market, your emergency fund is your “opportunity fund.” It allows you to quit a toxic job, move for a better position, or handle a medical emergency without dipping into your 13% investment pool. Placing this fund in a High-Yield Savings Account (HYSA) ensures that even your “idle” cash is working to combat inflation.
Debt Management: The High-Interest Trap
Half of 26 (13) is also a warning number for interest rates. Any debt with an interest rate above 7-8%—and certainly anything reaching the double digits—is a financial emergency. At 26, the priority should be the “Avalanche Method”: paying off the highest interest debt first while maintaining minimum payments on the rest. Eliminating credit card debt and high-interest private student loans is the equivalent of a guaranteed return on investment.
Revenue Streams and the Side Hustle Economy
Relying on a single source of income at 26 is a risk that many can no longer afford to take. The concept of “Half of 26” can also apply to your time management. If you spend 40 hours a week on your primary career, can you spend a fraction of that time—perhaps 13 hours a month—on a secondary revenue stream?
High-ROI Skill Development
The best investment a 26-year-old can make is in their own earning potential. This is the age to double down on “stackable skills.” If you are in marketing, learn data analytics. If you are in coding, learn project management. Increasing your primary salary is often easier than managing a complex portfolio of side hustles. A 10% raise at your day job usually yields more net profit than a sporadic freelance gig, and it requires less overhead.
Passive Income Foundations
At 26, the goal of a side hustle should eventually be the creation of passive income. This could include:
- Dividend Growth Investing: Reinvesting dividends to buy more shares.
- Content Creation: Building an audience that can be monetized through affiliate marketing or digital products.
- Real Estate: Saving for a down payment on a duplex or “house hacking” to reduce living expenses.
The “half of 26” mindset encourages you to think in terms of leverage. How can you do the work once and get paid for it 13 times over?
Long-Term Vision: Scaling Beyond the Quarter-Life Crisis
Many people hit a “quarter-life crisis” around age 26, feeling a sense of dread about their career trajectory or financial status. However, this is precisely the moment to zoom out and look at the macro-level of your financial life.
The Three-Year Rule
At 26, you are roughly three years away from the end of your twenties. Use this “half of a half” period to set non-negotiable targets. Where do you want your net worth to be at 29? By setting a three-year goal, you make the target tangible. It isn’t a vague “I want to be rich” sentiment; it’s a “I want to have $50,000 in my 401(k) and a $15,000 emergency fund by my 30th birthday.”
Building a Financial Legacy
Finally, 26 is the age to start thinking about “financial hygiene.” This includes setting up a simple will, designating beneficiaries on all accounts, and perhaps most importantly, automating your finances. Automation is the antidote to human error. If your 13% investment, your rent, and your savings are all moved automatically on payday, you remove the “choice” to overspend.
In conclusion, “what half of 26” is more than a calculation; it is a philosophy of balance. It is about allocating 13% to your future, spending 50% on your present, and utilizing the remaining 37% to pay off the past and enjoy the journey. By mastering these ratios at 26, you aren’t just surviving your twenties; you are engineering a lifetime of wealth and autonomy. The decisions made at this “pivot point” will resonate for the next 13 years and beyond, determining whether you reach 40 with a mountain of debt or a mountain of assets.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.