
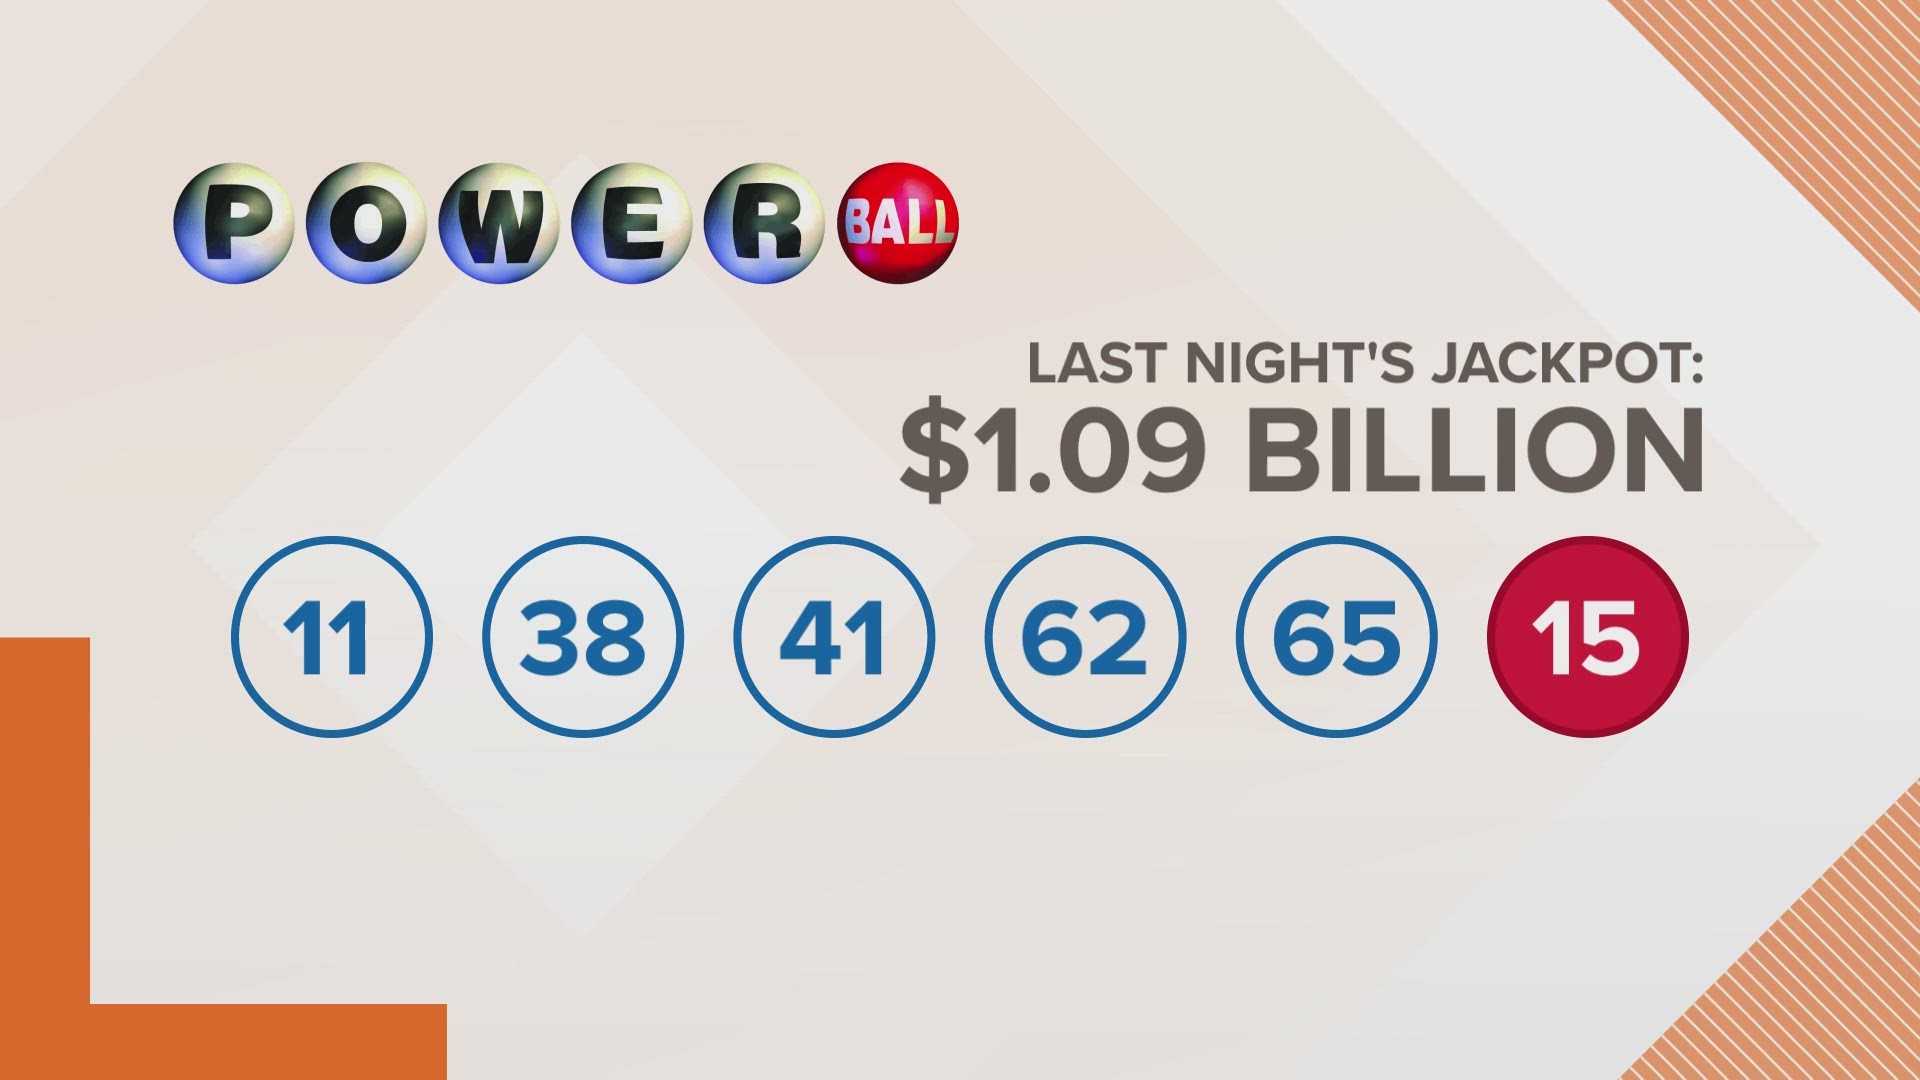
The search for “what was yesterday’s powerball numbers” is more than just a quest for digits; for many, it represents the intersection of hope and financial transformation. Whether you are checking a ticket out of habit or because you realized a local retailer sold a winning jackpot, the moment those numbers align with the slip in your hand, your financial reality shifts from conventional budgeting to high-stakes wealth management. In the world of personal finance, a lottery win is the ultimate “windfall event,” a sudden influx of capital that requires a sophisticated strategy to ensure that a once-in-a-lifetime stroke of luck translates into multi-generational security.

The Mechanics of the Lottery in the Context of Personal Finance
From a strictly mathematical standpoint, the lottery is often described by economists as a “tax on those who are bad at math.” However, in the broader scope of personal finance, it is more accurately categorized as a form of high-risk entertainment. Understanding the financial mechanics of the Powerball is the first step in maintaining a healthy relationship with wealth, whether you are a regular player or a one-time dreamer.
Understanding the Odds and the “Voluntary Tax”
The odds of winning the Powerball jackpot stand at approximately 1 in 292.2 million. To put this into a financial perspective, you are significantly more likely to be struck by lightning or to become a self-made billionaire through traditional entrepreneurship than you are to hit the grand prize. In personal finance circles, the money spent on lottery tickets is often viewed as “leaked capital”—funds that could otherwise be directed toward a Roth IRA, a high-yield savings account, or a diversified index fund.
While the occasional $2 ticket is a negligible expense for most, the aggregate spending on lotteries can reach thousands of dollars over a lifetime for some individuals. For a disciplined investor, the opportunity cost of these funds, when compounded over thirty years at an average market return of 7%, is substantial. Therefore, the first rule of lottery participation in a sound financial plan is to treat it as a discretionary entertainment expense, never as a replacement for a legitimate retirement strategy.
The Psychology of the Windfall Search
Searching for yesterday’s numbers triggers a dopamine response. This “near-miss” phenomenon or the anticipation of a win can lead to irrational financial behaviors. Professionals in the field of behavioral finance note that individuals often treat “found money” or “windfall money” differently than “earned money.” This is known as mental accounting. When people check their numbers and see a small win—perhaps $4 or $100—they are more likely to spend it impulsively rather than reinvesting it or using it to pay down debt. Recognizing this bias is crucial for maintaining overall financial health.
Immediate Steps After Verifying Your Numbers
If you check the numbers and find that you have indeed won a significant sum, the transition from a standard earner to a high-net-worth individual begins immediately. The “golden hour” following the discovery of a winning ticket is critical for protecting your new assets.
Securing the Asset and Establishing Privacy
The physical ticket is a “bearer instrument,” meaning that, in many jurisdictions, whoever holds the ticket owns the prize. Before calling friends or posting on social media, the most important financial move is to sign the back of the ticket (if permitted by state law) and place it in a secure location, such as a fireproof safe or a bank safety deposit box.
Simultaneously, privacy becomes your greatest financial shield. In the world of high finance, “stealth wealth” is a protective strategy. Once the public becomes aware of a massive windfall, the winner often becomes a target for predatory “investments,” frivolous lawsuits, and aggressive requests for loans from acquaintances. Maintaining anonymity, or at least extreme discretion, allows you the time to build a professional “moat” around your new fortune.
Resisting the Urge for Immediate Lifestyle Inflation
The most common financial pitfall for lottery winners is immediate lifestyle inflation. Purchasing luxury real estate, exotic cars, or high-end jewelry before the funds have even cleared is a recipe for the “lottery curse.” From a personal finance perspective, the first 90 days after winning should be a “quiet period.” During this time, your focus should not be on spending, but on the structural organization of your new financial life. No major purchases should be made until a comprehensive long-term financial plan has been drafted and vetted by professionals.
Strategic Windfall Management: Lump Sum vs. Annuity
One of the most significant financial decisions a Powerball winner faces is how to receive the payout. This choice is a classic exercise in the time value of money, tax planning, and behavioral discipline.
The Mathematics of the Lump Sum
Choosing the lump sum, or “cash option,” provides the winner with the present value of the jackpot all at once. For a savvy investor, this is often the preferred route. By taking the cash up front, you gain immediate control over the capital, allowing you to deploy it into a diversified portfolio of stocks, bonds, real estate, and private equity.
The primary advantage here is the potential for compound interest. If the market performs well, the total value of your investments over 30 years could far exceed the total value of the annuity payments. However, this requires immense discipline. The risk of the lump sum is “liquidity risk”—having too much cash available can lead to rapid depletion if not managed within a strict trust or corporate structure.
The Security of the Annuity
The Powerball annuity is paid out in 30 graduated installments over 29 years, with each payment increasing by 5%. From a financial planning perspective, the annuity offers a “safety net” against total ruin. If a winner makes poor investment choices or spends recklessly in the first few years, they still have a guaranteed stream of income arriving every year for three decades.
This option is often recommended for individuals who do not have experience managing large sums of money or who fear they may be pressured into giving away too much of their wealth too soon. Additionally, the annuity can potentially offer tax advantages if future tax rates remain stable or decrease, as it prevents the winner from being taxed on the entire amount in a single calendar year at the highest current bracket.
Building a Resilient Financial Infrastructure
A multi-million dollar win necessitates moving beyond basic banking. You are no longer just a “customer” of a bank; you are a “principal” who requires a specialized team to manage risk and growth.
Assembling Your Professional “Brain Trust”
To manage a windfall effectively, you must hire three key professionals immediately:
- Tax Attorney: To navigate the complex state and federal tax liabilities and to explore the use of trusts (such as Irrevocable Life Insurance Trusts or Charitable Remainder Trusts) to minimize the “tax bite.”
- Certified Public Accountant (CPA): To handle the immediate tax filings. A jackpot win can put you in the highest federal tax bracket (37%), and state taxes can take an additional 5-10% depending on where you live.
- Fee-Only Financial Advisor: Unlike advisors who work on commission, a fee-only fiduciary has a legal obligation to act in your best interest. They will help you create an Investment Policy Statement (IPS) that dictates how your money is allocated based on your goals and risk tolerance.
Debt Elimination and Asset Allocation
The first productive use of windfall funds is the elimination of “toxic debt”—high-interest credit cards, personal loans, and variable-rate mortgages. Clearing these liabilities provides an immediate, guaranteed “return” on your money by eliminating interest payments.
Once debt-free, the focus shifts to asset allocation. A common strategy for sudden wealth is the “Core and Satellite” approach. The “Core” consists of low-cost, broad-market index funds and government bonds that provide stability and steady growth. The “Satellite” portion—usually no more than 10-15% of the total wealth—can be used for higher-risk ventures, such as venture capital, angel investing, or speculative real estate, satisfying the urge for active investment without risking the foundational capital.
Avoiding the “Lottery Curse”: Sustainable Wealth Practices
The headlines are filled with stories of winners who went bankrupt within a decade. These failures are rarely due to a lack of money, but rather a lack of financial systems.
The Importance of a “No” Committee
One of the most effective tools for a high-net-worth individual is a “No” committee. When friends, family, or “entrepreneurs” approach you with “can’t-miss” business opportunities or requests for money, you can simply say, “I’d love to help, but my board of advisors handles all my financial requests, and they’ve set a strict budget for this year.” This shifts the emotional burden away from you and onto your professional team, preserving your personal relationships while protecting your capital.
Estate Planning and Generational Wealth
Checking yesterday’s numbers could be the start of a legacy that lasts for centuries. Sophisticated estate planning allows you to move beyond your own needs to consider your children, grandchildren, and philanthropic goals. Utilizing structures like Dynasty Trusts can protect assets from creditors and divorce while ensuring that the wealth is used for education and productive purposes rather than encouraging “trust fund” inertia.
In conclusion, “what was yesterday’s powerball numbers” is a query that opens the door to a complex world of high-level personal finance. Whether you hold the winning ticket or are simply planning for the possibility, the principles remains the same: wealth is preserved through discipline, professional guidance, and a long-term strategic vision. Winning the lottery is a matter of luck, but staying wealthy is a matter of financial education and execution.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.