
In the fast-paced world of personal finance, certain daily rituals capture the attention of millions. For many, the question “What was the midday cash 3 number?” is more than just a passing curiosity; it is a check-in on a micro-investment, a moment of anticipation that bridges the gap between daily budgeting and the hope for a tactical windfall. While the specific three-digit sequence changes every afternoon, the financial ecosystem surrounding these games is a complex intersection of probability, behavioral economics, and disciplined money management.
To understand the midday draw is to understand a specific niche of the gaming industry that relies on high-frequency, low-stakes participation. Unlike massive multi-state jackpots that reach into the billions, “Pick 3” or “Cash 3” games are the bread and butter of state-run lotteries, providing a steady stream of revenue for public projects while offering players a localized, manageable form of financial risk.
The Mechanics of Daily Draw Games and Their Economic Impact
Daily draw games like Cash 3 operate on a fundamental principle of probability that is essential for any financially literate individual to grasp. In a standard Cash 3 game, three chambers—each containing balls numbered 0 through 9—are used to select a winning sequence. Because each digit is drawn independently, there are exactly 1,000 possible combinations (000 through 999).
Understanding the House Edge and Payout Ratios
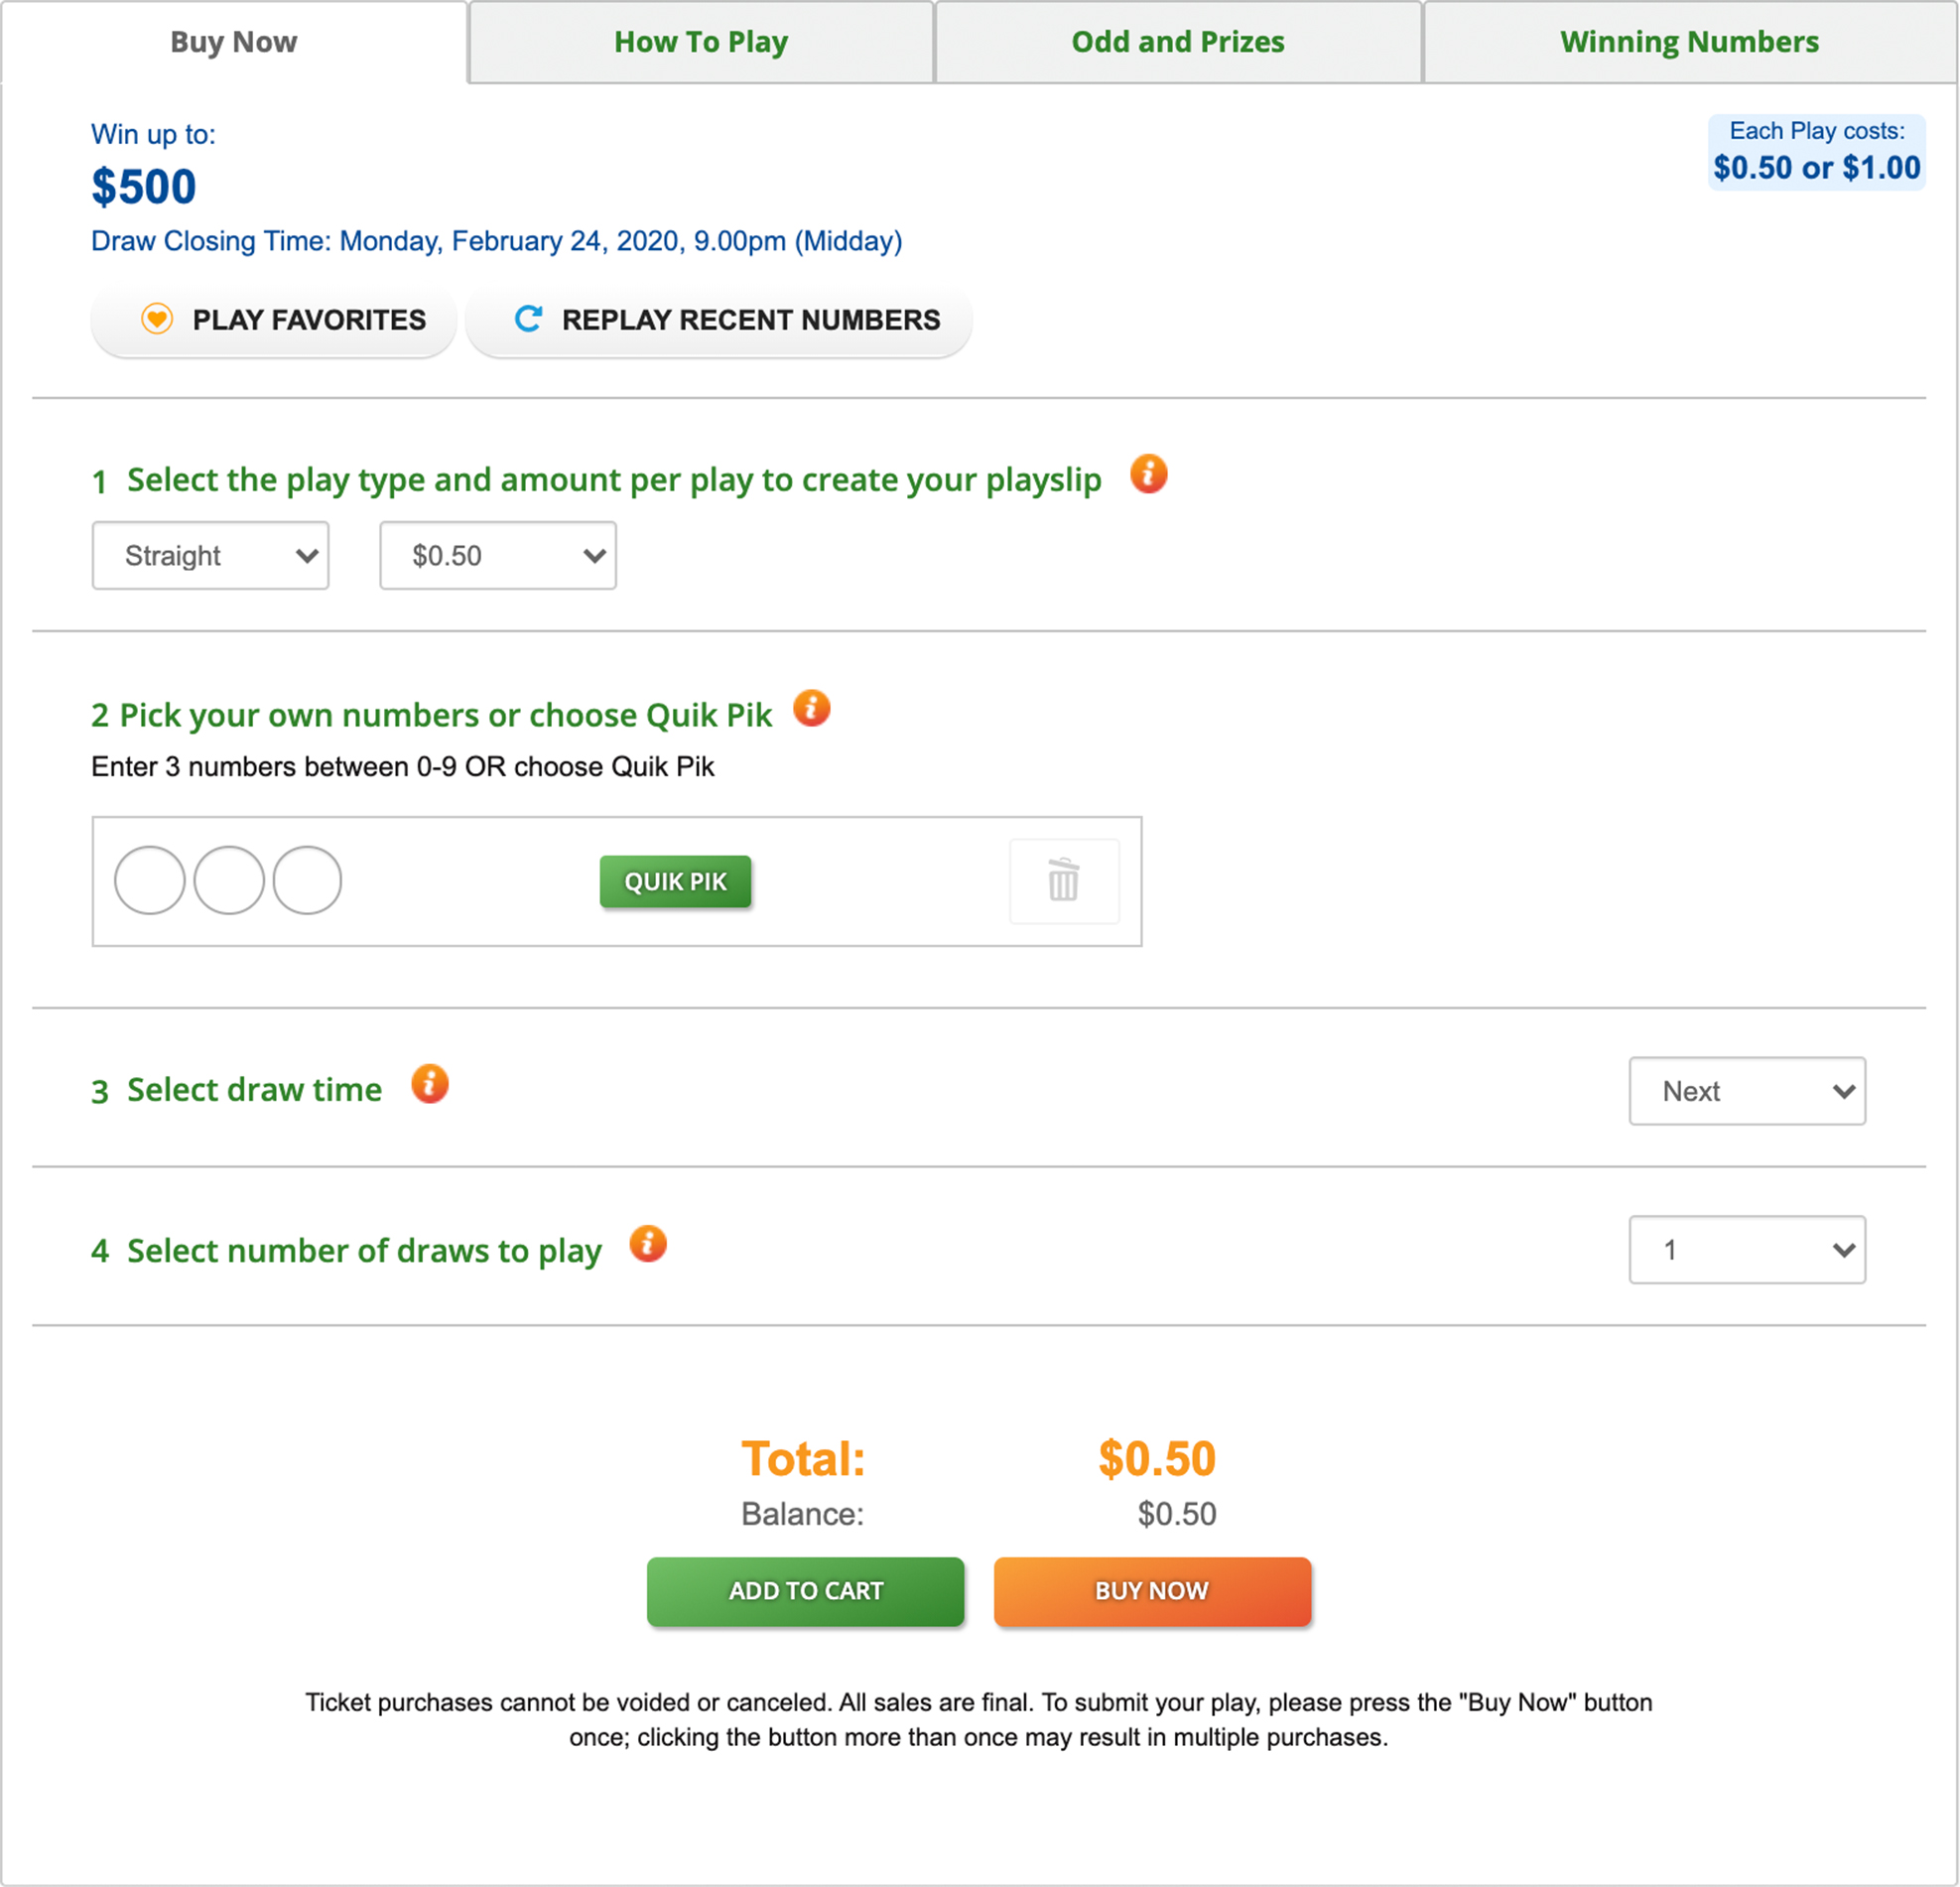
From a professional financial perspective, the “Cash 3” game is a study in “expected value.” Typically, a $1 “straight” bet (where the numbers must match in exact order) pays out approximately $500. While a 500-to-1 payout sounds lucrative, the mathematical reality is that the odds of winning are 1 in 1,000. This creates a 50% payout rate, meaning that for every dollar the state collects, fifty cents are returned to players in the form of prizes, while the remainder covers administrative costs and public funding.
Comparing this to other financial instruments is enlightening. While a standard savings account or a diversified stock portfolio aims for a positive expected return over time, gaming is statistically designed for a negative return. However, within the “Money” category of personal finance, many individuals treat these games as “entertainment expenses” rather than core investments. Understanding this distinction is the hallmark of sound financial planning.
The Role of Midday vs. Evening Draws
The introduction of the “midday” draw was a strategic move by lottery commissions to increase “velocity”—a term used in finance to describe how quickly money moves through a system. By doubling the frequency of draws, agencies can capture different demographic segments: the lunch-break player and the after-work player. This increased frequency requires players to be even more diligent with their tracking and budgeting, as the cost of participation can double without a corresponding increase in the probability of a win.
The Psychology of the “Quick Win” in Personal Finance
The search for the midday number often stems from a psychological phenomenon known as the “near-miss effect.” In financial psychology, humans are wired to find patterns even where none exist. When a player’s chosen number is 456 and the midday result is 457, the brain often interprets this as a “close win” rather than a total loss, encouraging further participation.
Behavioral Economics and Small-Stakes Gaming
In the broader context of online income and side hustles, the appeal of Cash 3 lies in its low barrier to entry and immediate liquidity. Unlike a high-yield certificate of deposit (CD) that might lock money away for years, or a volatile cryptocurrency that requires constant monitoring, a midday draw offers a definitive answer within hours.
For some, the small wins associated with “Box” bets (where numbers can appear in any order) serve as a psychological boost. Financially, however, these wins are often reinvested back into the game. Professional financial advisors often suggest that individuals interested in these games should treat them as a “sunk cost”—money that is gone the moment it is spent—to prevent the “sunk cost fallacy” from draining a primary savings account.
The Gamification of Budgeting
Interestingly, the rise of digital financial tools has led to the “gamification” of saving, which mirrors the excitement of a daily draw. Many modern fintech apps now offer “prize-linked savings accounts” (PLSAs). Instead of a traditional interest rate, these accounts offer participants the chance to win a daily or monthly draw based on how much they save. For the individual asking “What was the midday number?”, transitioning this interest into a PLSA can be a transformative financial move, shifting the focus from speculative spending to wealth accumulation.
Strategic Allocation: How to Manage “Fun Money”
Successful financial management is not about total deprivation; it is about the strategic allocation of resources. Within a robust personal finance framework, there is usually a category for “discretionary spending” or “entertainment.” This is where daily draw games must live.
The 50/30/20 Rule Applied
A common financial guideline is the 50/30/20 rule: 50% of income for needs, 30% for wants, and 20% for savings and debt repayment. If an individual is consistently checking the midday Cash 3 results, that expenditure must come strictly from the 30% “wants” category. Problems arise when speculative gaming begins to migrate into the “needs” or “savings” categories.
Digital Tracking and Transparency
In the age of digital banking, it has never been easier to track the impact of daily gaming on a budget. Using spreadsheets or dedicated financial apps to record every dollar spent on draws versus every dollar won provides a clear “Profit and Loss” (P&L) statement. Often, seeing the cumulative annual spend on midday draws is the catalyst a person needs to redirect those funds toward a more productive side hustle or an automated investment platform.
Leveraging Technology to Monitor Results and Finances
The way people discover the midday Cash 3 number has evolved from checking the back of a newspaper to receiving real-time mobile alerts. This shift toward instant information mirrors the broader trends in “FinTech” (Financial Technology), where speed and accessibility are paramount.
Official Apps vs. Third-Party Aggregators
Most state lotteries now offer official apps that not only provide the winning numbers but also allow for “e-plays” and ticket scanning. From a digital security perspective, using official channels is vital. Third-party sites that claim to predict “hot” or “cold” numbers are often predatory, charging fees for information that is, by the laws of physics and mathematics, purely random. In the world of money management, paying for “winning tips” is considered a high-risk, low-reward expense that should be avoided.
Integrating Results into Wealth-Building Strategies
For the disciplined player, a win in the midday draw should be treated as “found money.” In professional finance, found money—whether it be a lottery win, a tax refund, or a work bonus—is best utilized by applying it to high-interest debt or a retirement account.
If a midday Cash 3 win nets $500, the immediate “professional” move is to consider its future value. If that $500 were placed into a Roth IRA with an average 7% annual return, it could grow significantly over several decades. This perspective shifts the midday number from a moment of temporary excitement to a building block for long-term financial independence.
The Macro-Economics of the Midday Draw
Beyond the individual player, the daily midday number plays a role in the larger economy of a state or region. Lottery revenues are frequently earmarked for specific public sectors, such as education, senior citizen services, or infrastructure.
Social Responsibility and Corporate Identity
State lotteries function as a unique brand of “socially conscious” gaming. By marketing themselves as supporters of the “common good,” they maintain a corporate identity that is distinct from private casinos. For the taxpayer, understanding where this “midday money” goes is a form of civic financial literacy. It allows citizens to see the direct link between a $1 ticket and the funding of a local scholarship or a public park.
The Future of Daily Draws and Digital Currency
As the financial world moves toward Central Bank Digital Currencies (CBDCs) and blockchain technology, the way daily draws are conducted may change. We may see a future where the “midday number” is generated via a transparent, verifiable smart contract on a blockchain, ensuring absolute randomness and immediate, automated payouts to digital wallets. This evolution would align the traditional daily draw with the modern trends of “DeFi” (Decentralized Finance), offering a level of security and efficiency that current paper-based systems cannot match.
Conclusion: Balancing Curiosity with Financial Discipline
The question “What was the midday cash 3 number?” is a reflection of a deeply ingrained human interest in luck and timing. However, when viewed through the lens of professional money management, it serves as a reminder of the importance of probability, budgeting, and the “time value of money.”
By treating the daily draw as a controlled discretionary expense rather than a viable financial plan, individuals can enjoy the ritual without compromising their economic future. The true “winning number” in personal finance is not found in a midday draw, but in the consistent, disciplined application of saving, investing, and informed decision-making. Whether the midday result is 123, 789, or 000, the most successful players are those who have a diversified financial portfolio that doesn’t rely on the luck of the draw.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.