
In the landscape of personal finance and wealth management, the concept of a “multivitamin” serves as a powerful metaphor for a diversified investment portfolio. Just as a physical multivitamin is designed to provide a comprehensive spectrum of essential nutrients to ensure bodily health and prevent deficiencies, a financial multivitamin represents the balanced collection of assets, strategies, and safeguards necessary to maintain fiscal vitality. To achieve long-term financial independence, one cannot rely on a single “nutrient” like a high-yield savings account or a volatile tech stock. Instead, a robust financial plan requires a calculated blend of growth, stability, liquidity, and protection.
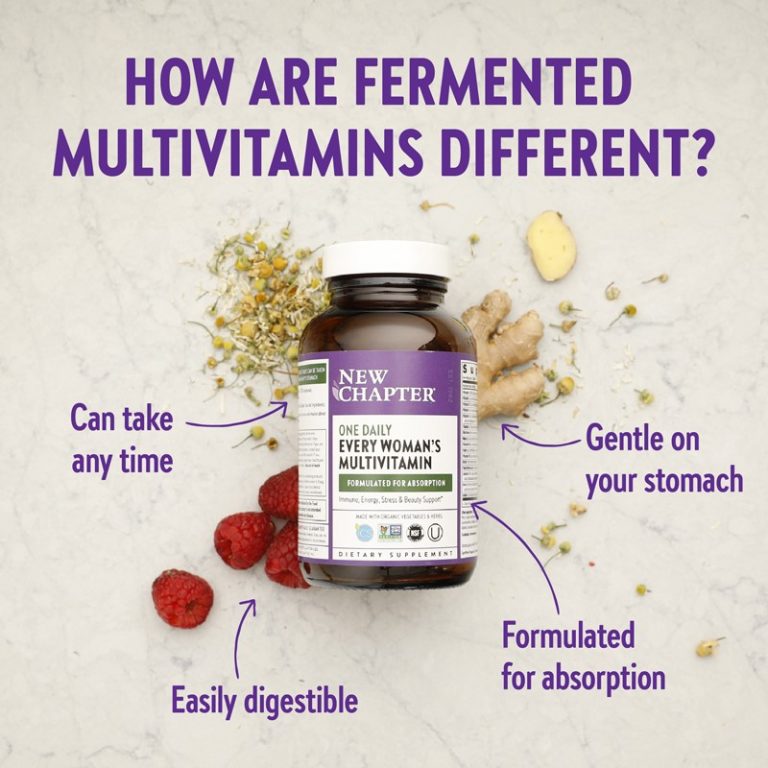
When we ask what “vitamins” are in a financial multivitamin, we are essentially identifying the core components of a resilient wealth-building strategy. Each component serves a distinct purpose, and when combined, they create a synergistic effect that protects against market volatility while capitalizing on long-term growth trends.
The Foundation of Liquidity: Vitamin C for Financial Certainty
In the world of finance, “Vitamin C” stands for Cash and Certainty. This is the most fundamental ingredient in any financial multivitamin. Without a foundation of liquid assets, the entire financial structure becomes brittle and prone to collapse during economic storms.
The Emergency Fund: The Essential Micronutrient
The emergency fund is the first “vitamin” any investor should secure. It acts as a buffer against the unforeseen—job loss, medical emergencies, or urgent home repairs. Financial experts generally recommend maintaining three to six months of essential living expenses in a highly liquid form, such as a high-yield savings account (HYSA) or a money market fund. This ensures that when life’s inevitable stressors occur, you are not forced to liquidate long-term investments at a loss. In a “financial multivitamin,” this component provides the peace of mind necessary to stay invested during market downturns.
Cash Equivalents and Short-Term Treasury Bills
Beyond the emergency fund, a strategic allocation to cash equivalents offers flexibility. In an environment of fluctuating interest rates, short-term Treasury bills (T-Bills) or Certificates of Deposit (CDs) can serve as “supplemental” liquidity. These instruments offer a higher yield than standard checking accounts while maintaining a near-zero risk profile. By keeping a portion of the “multivitamin” in these liquid assets, investors retain “dry powder”—the ability to seize investment opportunities when asset prices drop.
Growth and Appreciation: The Macro-nutrients of Wealth
If liquidity is the foundation, then equities are the macro-nutrients that provide the energy for wealth to grow. Just as the body requires carbohydrates and proteins for energy and repair, a financial portfolio requires growth-oriented assets to outpace inflation and build substantial net worth over decades.
Low-Cost Index Funds: The Daily Requirement
The backbone of the growth component in a financial multivitamin is the low-cost index fund. Whether it tracks the S&P 500 or the total stock market, index funds offer broad exposure to the most successful companies in the world. By diversifying across hundreds or thousands of companies, the investor mitigates the “single-stock risk” that can devastate a portfolio. These funds are the “daily multivitamin” of the investment world—simple, effective, and scientifically proven to outperform most active management strategies over long horizons.
Growth Stocks and Sector-Specific Supplements
For those with a higher risk tolerance and a longer time horizon, growth stocks represent a high-potency “vitamin” boost. These are companies—often in the technology, biotech, or clean energy sectors—that reinvest their earnings into expansion rather than paying dividends. While more volatile, these assets provide the “alpha” or outsized returns that can significantly accelerate the path to financial independence. In a balanced multivitamin approach, growth stocks are balanced by more stable “value” stocks, ensuring the portfolio doesn’t become overly reliant on a single market trend.
Stability and Income: Vitamin D for Duration and Dividends
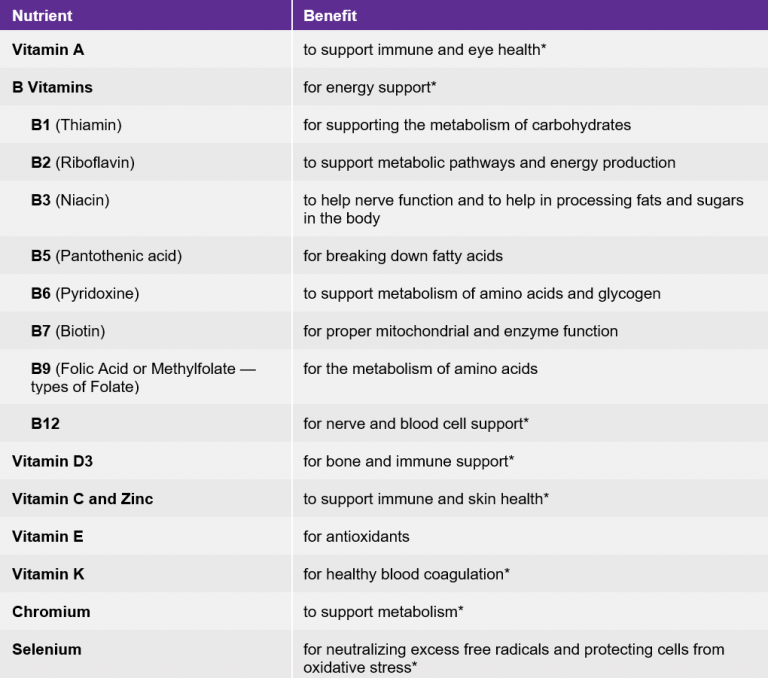
Stability is the “Vitamin D” of finance, providing the structural integrity needed to withstand the weight of market cycles. As an investor matures, the need for consistent income and capital preservation increases, making these “vitamins” indispensable.
Fixed Income and the Bond Market
Bonds are the traditional stabilizers of a financial multivitamin. When the stock market experiences high volatility, high-quality government and corporate bonds often move in the opposite direction or remain steady. This inverse correlation is essential for reducing the overall “beta” or volatility of a portfolio. By including a mix of short-term and long-term bonds, investors can ensure that their wealth is protected while still earning a modest yield.
Dividend-Paying Equities: The Passive Income Stream
Dividend stocks provide a unique hybrid of growth and income. Companies that consistently pay and increase dividends—often referred to as Dividend Aristocrats—demonstrate financial maturity and reliable cash flow. For a financial multivitamin, dividends represent the “slow-release” nutrient that provides a steady stream of passive income, regardless of whether the share price is up or down. Reinvesting these dividends creates a powerful compounding effect, significantly increasing the total “dosage” of wealth over time.
Protection and Tax Efficiency: The Financial Immune System
A truly comprehensive multivitamin does more than just promote growth; it protects the system from external threats. In finance, these threats include taxes, inflation, and legal liabilities. Without an “immune system” of protection, a large portion of an investor’s gains can be eroded.
Tax-Advantaged Accounts: Maximizing Absorption
How you hold your assets is just as important as what assets you hold. Tax-advantaged accounts like 401(k)s, IRAs, and Health Savings Accounts (HSAs) act as the “delivery system” for your financial vitamins, ensuring that the maximum amount of capital is absorbed into your net worth rather than being lost to the IRS. By utilizing Roth conversions or tax-loss harvesting, investors can optimize their “tax alpha,” essentially gaining a higher net return without taking on additional market risk.
Insurance and Estate Planning: The Protective Coating
A financial multivitamin is incomplete without the “protective coating” of insurance. Life, disability, and long-term care insurance protect the human capital—the ability to earn an income—which is often an individual’s most valuable asset. Furthermore, estate planning ensures that the wealth accumulated is transferred efficiently to the next generation, preventing it from being “metabolized” by probate costs and estate taxes.
Alternative Assets: The Rare Minerals of the Portfolio
In addition to the standard vitamins, many high-performance financial plans include “rare minerals” or alternative assets. These are investments that do not always move in sync with the traditional stock and bond markets, providing an extra layer of diversification.
Real Estate: Tangible Value
Real estate is a classic alternative asset that offers three distinct benefits: rental income, capital appreciation, and significant tax advantages through depreciation. Whether through direct ownership or Real Estate Investment Trusts (REITs), adding real property to a financial multivitamin provides a hedge against inflation, as property values and rents typically rise alongside consumer prices.
Digital Assets and Commodities
In the modern era, many investors are adding small “dosages” of digital assets like Bitcoin or commodities like gold to their financial multivitamin. Gold has historically served as a store of value during times of geopolitical instability, while digital assets represent a bet on the future of decentralized finance. While these are considered “high-potency” and should be used sparingly, they provide a level of non-correlation that can protect a portfolio from systemic shocks in the traditional banking system.
Maintaining the Regimen: The Importance of Rebalancing
Just as a physical multivitamin is only effective if taken consistently, a financial multivitamin requires regular maintenance and “re-dosing.” This process is known as rebalancing. Over time, high-performing assets (like growth stocks) will begin to represent a larger percentage of the portfolio, while underperforming or stable assets (like bonds) will shrink.
If left unchecked, this “nutrient imbalance” increases the risk profile of the investor beyond their comfort level. By periodically selling a portion of the winners and buying more of the underperformers, the investor adheres to the most fundamental rule of finance: buy low and sell high. This disciplined approach ensures that the “multivitamin” remains perfectly calibrated to the individual’s age, goals, and risk tolerance.
In conclusion, “what vitamins are in a multivitamin” in a financial context refers to the strategic combination of liquidity, growth, stability, protection, and diversification. By ensuring each of these “nutrients” is present in the correct proportions, an individual can build a financial life that is not only resistant to the occasional economic “virus” but is also robust enough to thrive across every season of the market. Success is not found in a single miracle stock, but in the consistent, balanced application of these essential financial vitamins.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.