
In the world of personal finance and wealth management, the term “high cholesterol” serves as a potent metaphor for the accumulation of toxic assets, high-interest liabilities, and inefficient fiscal habits that clog the arteries of your cash flow. Just as biological cholesterol can build up silently over years before causing a systemic crisis, financial “cholesterol” often accumulates unnoticed through small, recurring decisions. When your portfolio’s health is at risk, the remedy isn’t just about adding new assets; it is primarily about knowing what to stay away from.
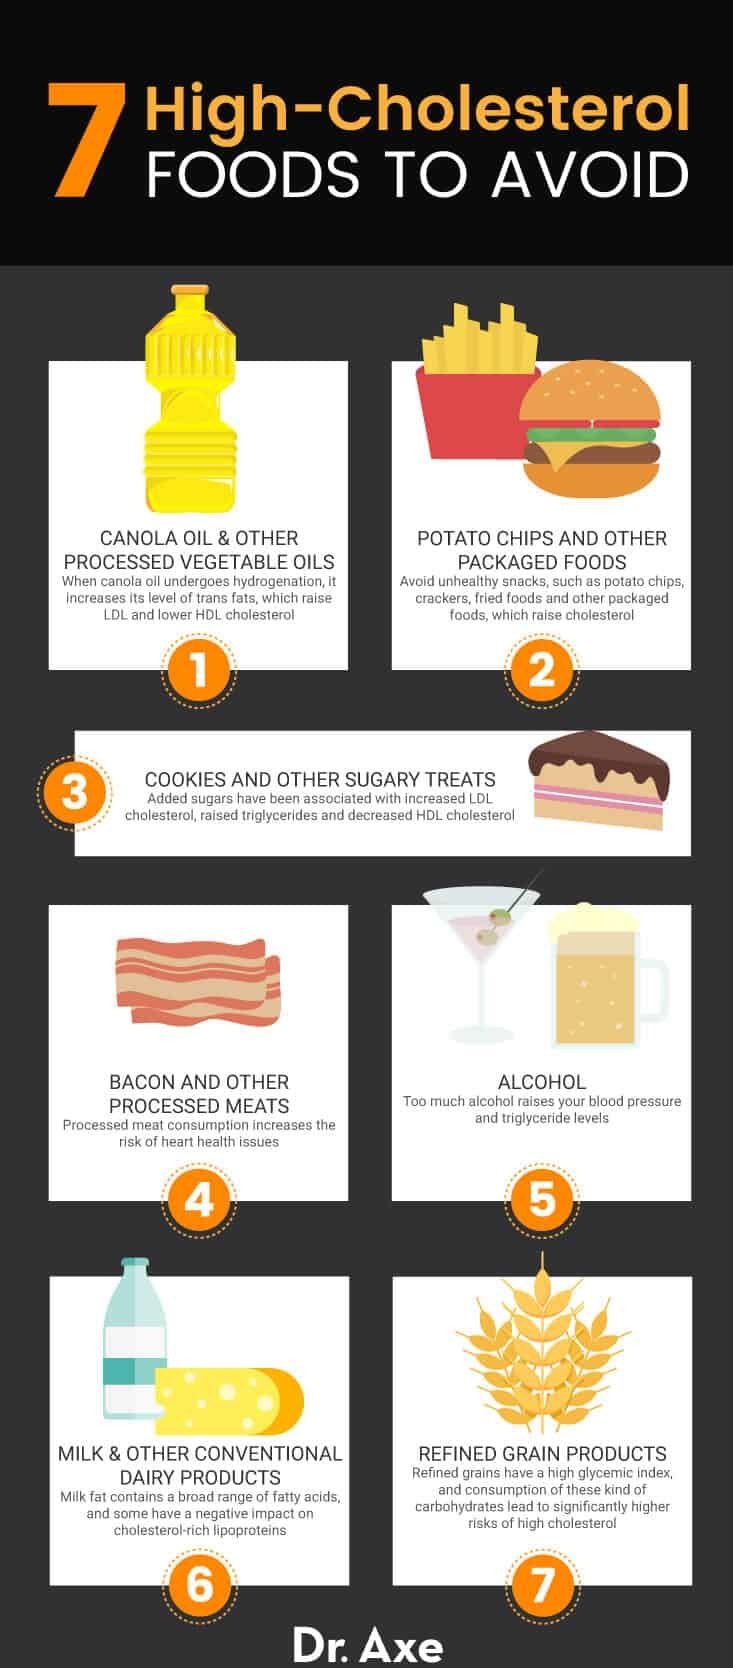
Maintaining a lean, efficient financial profile requires a disciplined approach to identifying “saturated fats”—those high-cost, low-value commitments that drain your net worth. To achieve long-term fiscal vitality, an investor must be ruthless in purging elements that hinder liquidity and stifle growth. This guide explores the critical areas of personal and business finance that you must avoid to ensure your economic heart remains strong.
The Clogged Arteries of High-Interest Consumer Debt
The most dangerous form of financial cholesterol is high-interest consumer debt. Just as LDL cholesterol restricts blood flow, revolving credit and high-APR loans restrict the flow of capital toward wealth-building opportunities. When you carry a balance on a credit card with a 24% interest rate, you are effectively fighting against the most powerful force in finance: compounding. However, in this scenario, the compounding works against you, creating a self-sustaining cycle of liability that is difficult to break.
The Trap of Revolving Credit Lines
Revolving debt is the “trans-fat” of the financial world. It offers immediate gratification with long-term systemic damage. Staying away from credit card balances is the first step in any financial “detox.” The psychological danger of these accounts lies in the minimum payment trap. By paying only the minimum, the majority of your capital is redirected toward interest expenses rather than principal reduction. This ensures that the debt stays in your system for decades, siphoning off resources that could have been used for retirement or business investment.
Avoiding Predatory Lending and Payday Cycles
If credit cards are the saturated fats, payday loans and predatory short-term lending are the equivalent of pure poison. These instruments often carry annual percentage rates (APRs) exceeding 400%. They are designed to exploit temporary liquidity crises, but they almost always result in a permanent degradation of financial health. To stay away from this toxic debt, one must focus on building an emergency fund—the financial equivalent of an immune system—that can absorb shocks without requiring high-cost external intervention.
Trimming the Fat: High Fees and Portfolio Bloat
In the pursuit of investment growth, many individuals inadvertently invite “cholesterol” into their portfolios through high management fees and inefficient investment vehicles. Often, investors are so focused on the potential returns that they ignore the “friction” that erodes those returns over time. A 1% or 2% management fee may seem negligible in a single year, but over a 30-year investment horizon, it can consume nearly a third of your total wealth.
Actively Managed Funds with Poor Track Records
For the average investor, high-cost actively managed mutual funds are often something to stay away from. Data consistently shows that the vast majority of active managers fail to beat their benchmark indices over long periods, especially after accounting for fees and taxes. By choosing high-expense ratio funds, you are paying a premium for underperformance. To optimize your portfolio’s health, the focus should shift toward low-cost index funds and ETFs (Exchange-Traded Funds) that provide broad market exposure with minimal drag.
The Hidden Costs of “Wrapped” Financial Products
Variable annuities and complex life insurance products with investment components are often sold as comprehensive solutions, but they frequently contain layers of hidden fees, surrender charges, and administrative costs. These products are the “processed foods” of the financial industry—highly engineered, expensive, and often less beneficial than their simpler counterparts. To maintain a clean financial bill of health, stay away from products you do not fully understand or those that require a twenty-page disclosure to explain the fee structure.

Speculative Junk Food: FOMO and Unregulated Assets
In an era of digital connectivity, the temptation to indulge in “financial junk food” has never been higher. Speculative assets—driven by social media hype and the “Fear Of Missing Out” (FOMO)—can provide a temporary rush but often lead to a significant “crash” that damages your core capital. These assets lack the fundamental “nutrients” of earnings, dividends, or tangible utility.
Pump-and-Dump Schemes and Meme Assets
Staying away from assets that trade purely on sentiment is crucial for long-term stability. Meme stocks, certain micro-cap cryptocurrencies, and unvetted NFT projects often lack the structural integrity needed for a serious portfolio. These are highly volatile and susceptible to manipulation. While a small “cheat meal” of speculative play money might be acceptable for some, allowing these assets to become a primary component of your portfolio is the equivalent of a diet consisting solely of sugar. It leads to volatility that can cause emotional decision-making, which is the leading cause of permanent capital loss.
The Danger of Unregulated Platforms
Where you keep your money is just as important as what you invest in. Staying away from unregulated or offshore trading platforms is a vital safety measure. In the event of a platform failure or a “bank run,” assets held in unregulated environments may have no legal protections or insurance (such as FDIC or SIPC). For a healthy financial life, stick to established, transparent institutions that are subject to rigorous oversight.
Structural Risks: Inefficient Tax Planning and Low Liquidity
A high-cholesterol financial profile is often characterized by a lack of flexibility. When too much of your net worth is tied up in illiquid assets or exposed to unnecessary tax liabilities, your ability to react to market changes is severely hampered.
Over-Allocation in Non-Liquid Assets
While real estate and private equity can be excellent long-term investments, over-allocating in these areas can create a liquidity crisis. If you cannot access cash without selling a physical asset—a process that can take months and involve high transaction costs—you are financially “stiff.” Staying away from an over-concentration in illiquid holdings ensures that you can pivot when opportunities or emergencies arise. A healthy balance involves maintaining a “liquid core” of cash and publicly traded securities.
Ignoring the “Tax Drag”
Taxes are the ultimate persistent expense. Investors who ignore tax-loss harvesting or who trade frequently in high-tax environments are essentially letting their wealth leak away. Staying away from short-term capital gains whenever possible is a key strategy for maintaining “clean” growth. By utilizing tax-advantaged accounts like IRAs, 401(k)s, or HSAs, you protect your gains from the eroding effects of the tax man, allowing your “financial blood pressure” to remain at a sustainable level.

Developing a Regimen for Long-Term Wealth
Correcting “high cholesterol” in your finances is not a one-time event but a lifestyle change. It requires a move away from the “quick fix” mentality and toward a philosophy of sustainable, low-friction growth. This means prioritizing “whole foods”—assets with clear value, transparent costs, and proven track records.
To stay away from the pitfalls of financial bloat, one must perform regular “check-ups.” This involves:
- Auditing Recurring Expenses: Identifying and canceling subscriptions or services that no longer provide ROI.
- Rebalancing for Efficiency: Ensuring that your asset allocation hasn’t drifted into high-risk or high-cost territory.
- Refinancing High-Interest Liabilities: Aggressively targeting any debt that exceeds a reasonable market rate.
By being mindful of what to stay away from, you create a defensive perimeter around your wealth. Financial health is as much about what you don’t do as it is about what you do. By avoiding the toxic debt, high fees, and speculative manias that clog the system, you ensure that your capital remains vibrant, liquid, and ready to support your long-term goals. Wealth, much like physical health, is a marathon, and the cleanest runners—those without the weight of financial cholesterol—are the ones who ultimately cross the finish line in the best condition.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.