
Managing chronic inflammation is often framed through the lens of nutrition and medical intervention, yet there is a critical, overlooked aspect: the financial burden of sustained health management. When long-term wellness becomes a recurring line item in your budget, the stress of funding these treatments can ironically exacerbate the very inflammation you are trying to soothe. Building a robust financial framework to support health-related expenditures is essential for long-term stability and peace of mind.
Assessing the True Cost of Health Maintenance
To effectively budget for anti-inflammatory protocols, one must first transition from seeing health costs as unexpected emergencies to viewing them as predictable, necessary business expenses within your personal portfolio.

The Breakdown of Recurring Health Overhead
Anti-inflammatory health plans often involve a trifecta of recurring costs: premium nutrition, therapeutic supplements, and specialized services such as physical therapy or holistic consults. Begin by auditing your last six months of spending. Categorize these into “Essential Maintenance” (prescriptions, standard co-pays) and “Proactive Optimization” (supplements, ergonomic equipment, high-quality groceries). By isolating these figures, you can determine your “Base Health Burn Rate”—the minimum amount of capital required every month to maintain your current physical state.
Creating a Health-Specific Emergency Fund
Standard financial advice suggests a three-to-six-month emergency fund, but those managing inflammatory conditions often require a dedicated “Health Reserve.” This account acts as a buffer against insurance coverage gaps or sudden flare-ups that might require a pivot in treatment strategy. By ring-fencing this capital, you remove the psychological friction of deciding whether to pay for a necessary wellness appointment or cover a household bill, thereby reducing the cortisol spikes that frequently trigger inflammatory responses.
Tax-Advantaged Tools for Medical Capital
The financial landscape offers specific vehicles designed to help individuals offset the high cost of health management. If you are not utilizing these to their full capacity, you are effectively paying a “health premium” out of post-tax income that could otherwise be redirected toward your recovery.
Leveraging HSAs and FSAs
A Health Savings Account (HSA) is perhaps the most powerful tool for those managing chronic health concerns. Because contributions are tax-deductible, your money grows tax-deferred, and withdrawals for qualified medical expenses are tax-free. If you are in a high-deductible health plan, prioritize maximizing your HSA contributions before directing excess funds into general brokerage accounts. This acts as a long-term investment vehicle where the interest is your personal health longevity.
Understanding Medical Expense Deductions
For individuals whose health-related out-of-pocket costs exceed a certain percentage of their adjusted gross income, the IRS allows for the deduction of medical expenses that are not reimbursed by insurance. This includes not just doctor visits, but also specific dietary requirements if they are medically necessary and documented by a physician. Maintaining a meticulous digital ledger of receipts, invoices, and diagnostic referrals is not just good accounting—it is a defensive financial strategy that can lower your tax liability significantly at the end of the fiscal year.
Strategic Allocation of Professional Services

As your health journey progresses, you will likely encounter service providers—nutritionists, chiropractors, or wellness coaches—who promise relief. From a financial perspective, you must treat these as high-stakes investments rather than passive purchases.
Conducting a Financial ROI on Wellness Services
Just as a business evaluates the Return on Investment (ROI) for new software or a consultancy firm, you must evaluate the efficacy of your health providers. Set clear, measurable benchmarks for success. If a service does not yield measurable improvements in your inflammatory markers or daily functionality within a specified timeframe, you have the financial agency to terminate that service and reallocate those resources elsewhere. Avoid the “sunk cost fallacy” where you continue paying for an ineffective treatment simply because you have already invested significant funds into it.
Bulk Sourcing and Subscription Efficiency
Recurring health expenses are prime candidates for optimization through bulk purchasing and long-term subscription models. Many high-quality supplement manufacturers offer deep discounts for “subscribe and save” programs. While this involves a larger upfront cash outlay, the compounding savings over a twelve-month period can be substantial. Furthermore, look for professional-grade dispensaries that offer lower pricing for consistent users, effectively lowering your cost per unit without sacrificing the quality of the product—a key necessity when managing inflammation through high-grade inputs.
Insuring Against Future Volatility
Long-term management of inflammation requires a defensive posture regarding your ability to generate income. If your health fluctuates, your financial infrastructure must be robust enough to continue supporting your recovery without external pressure.
The Role of Disability and Long-Term Care Insurance
Often overlooked by younger professionals, disability insurance is arguably the most critical component of a health-oriented financial plan. If an inflammatory condition reaches a point where it interferes with your ability to work, your income stream is your most vulnerable asset. Ensure that your policy includes “own-occupation” coverage, which provides benefits if you cannot perform the specific duties of your current profession. This provides a safety net that protects your assets and allows you to focus on health, rather than financial panic, during a period of diminished capacity.
Future-Proofing Through Diversification
The ultimate financial goal in managing chronic health is to move from a state of reactive spending to one of sustainable stability. As your health stabilizes, reinvest the surplus capital from your health budget back into income-generating assets. By creating passive income streams—such as dividends, rental income, or royalties—you effectively create a permanent fund that covers your health costs. This transition is the pinnacle of financial health; it allows you to pay for your wellness not through the labor of your active hours, but through the growth of your capital, effectively creating a self-sustaining cycle of health and wealth.
Integrating Lifestyle Choices with Economic Efficiency
Finally, consider the hidden economic costs of inflammatory habits. Poor sleep, extreme stress, and processed-food dependence are not just physical issues—they are financial drains.
The Cost of Convenience
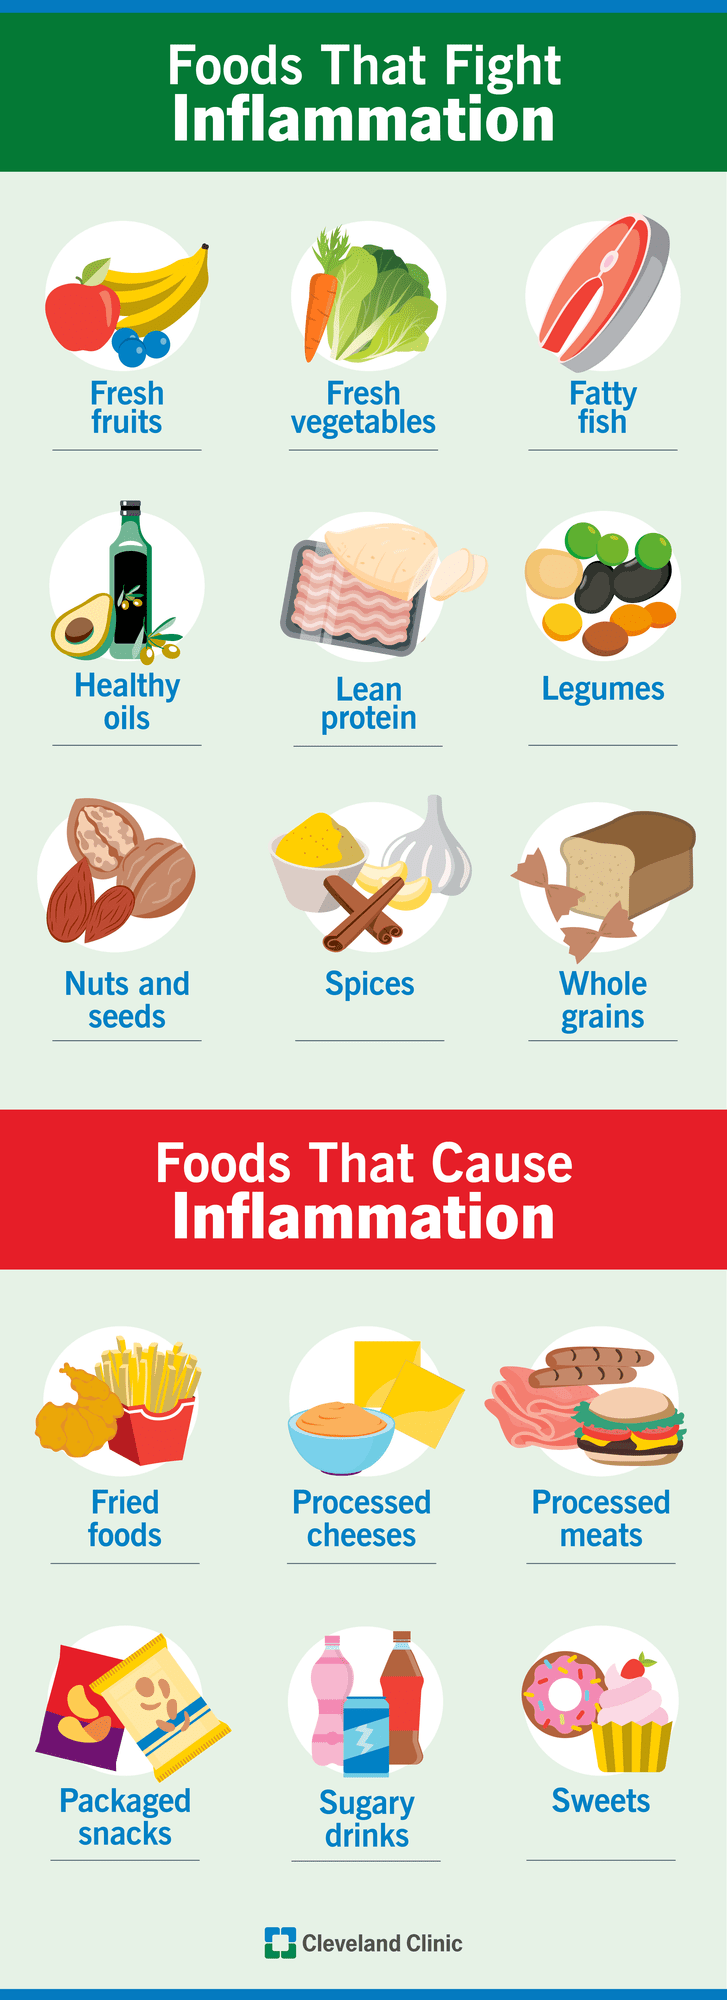
Many individuals pay a “convenience tax” by relying on processed foods or delivery services when they are too tired to prepare anti-inflammatory meals. By investing in time-saving kitchen tools or meal-prep strategies, you are essentially reducing your long-term medical expenditures. Every dollar spent on an air fryer, a high-quality blender, or a bulk-purchase membership is a dollar diverted from a future medical bill.
Wealth and Wellness Synergy
True recovery requires the removal of stress. By creating a transparent budget, automating your health savings, and utilizing tax-advantaged accounts, you eliminate the mental load associated with managing the cost of your care. When your financial house is in order, your nervous system remains calmer, your cortisol levels drop, and your body is physically better equipped to manage inflammation. Financial health is not merely a tool to pay for wellness; it is a foundational component of the wellness process itself. Your commitment to managing your financial resources with the same diligence you apply to your physical health will provide the stability necessary for lasting, systemic improvement.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.